
When you’ve built meaningful wealth — whether through a business exit, decades of executive compensation, or a successful professional career — you quickly discover that managing it well requires more than picking investments. A full-service financial advisor is the professional who coordinates every dimension of your financial life, from portfolio strategy to tax efficiency to estate structure, as one integrated plan.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
Too many affluent families are still working with advisors who only manage their brokerage account while critical gaps go unaddressed. Understanding what a truly comprehensive advisor does — and doesn’t do — is the first step toward knowing whether you’re getting the guidance your wealth deserves.
What Is a Full-Service Financial Advisor?
A full-service financial advisor is a credentialed professional who provides holistic, ongoing guidance across investments, tax strategy, retirement planning, estate planning, and risk management — not just portfolio management alone. Rather than selling you a product and moving on, they maintain an active, year-round relationship designed to coordinate all aspects of your financial picture and help you pursue your long-term goals.
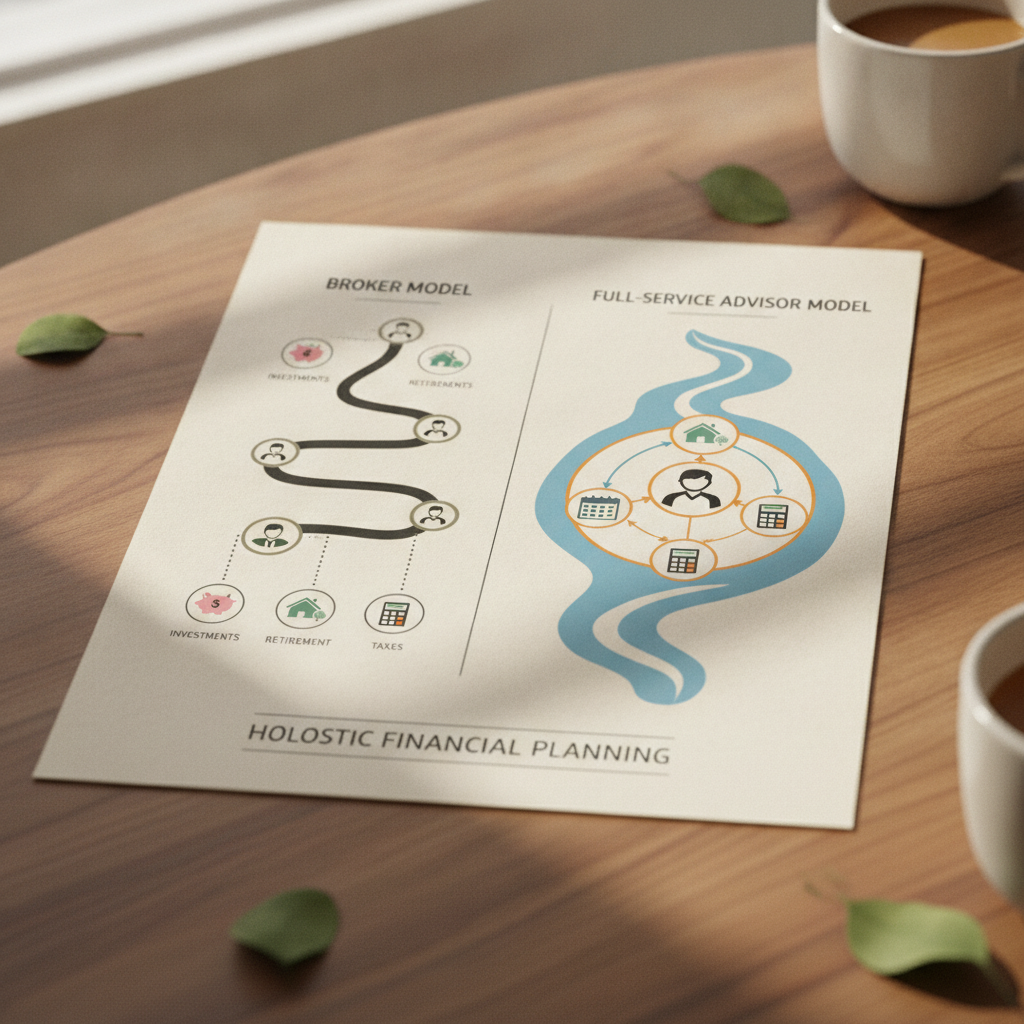
This model stands in contrast to transaction-based brokers, who are compensated by what they sell you, or narrow specialists who only advise on one slice of your financial life. The full-service model recognizes that every financial decision — a Roth conversion, a business sale, a charitable gift — ripples across your entire plan.
What Does a Full-Service Financial Advisor Actually Do?
The scope of a full-service relationship is significantly broader than most people realize. Here is what genuine comprehensive service looks like in practice.
Investment Management as a Full-Service Financial Advisor Delivers It
Portfolio management is the foundation, but a full-service advisor goes well beyond selecting funds. They build a tax-aware asset location strategy — placing assets in the right account types (taxable, traditional, Roth) to minimize your lifetime tax burden. For clients with concentrated stock positions, they develop systematic diversification strategies that balance tax cost against risk reduction.
They also monitor drift, rebalance with tax sensitivity, and conduct tax-loss harvesting when market conditions create the opportunity — a strategy that can be particularly meaningful for investors with portfolios over $1 million, where the dollar value of harvested losses is substantial.
Retirement Income Planning
Accumulation and distribution are fundamentally different disciplines. A full-service financial advisor helps high-net-worth clients think through Social Security claiming strategy, Required Minimum Distribution (RMD) sequencing, and sustainable withdrawal rates — all while keeping an eye on IRS RMD rules and how they interact with your tax bracket.
For executives and business owners, this includes integrating deferred compensation payouts, pension elections, and stock option exercise timing into the retirement income picture.
Tax Planning and Coordination
This is where full-service advising often delivers its greatest value for high-net-worth families. A comprehensive advisor works proactively — not just reactively at year-end — to identify opportunities like:
- Roth conversion ladders — strategically converting traditional IRA assets in lower-income years to reduce future RMD burden and long-term tax exposure
- IRMAA management — planning income carefully to avoid Medicare surcharges that can add thousands per year for high earners
- Qualified Charitable Distributions (QCDs) — allowing investors 70½ and older to give directly from an IRA, satisfying RMDs without increasing adjusted gross income
- Business structure tax efficiency — advising business owners on entity structure and retirement plan design to maximize deductions
Consult a qualified tax professional for your specific situation, as these strategies have eligibility requirements and trade-offs that vary based on individual circumstances.
Estate Planning Coordination
A full-service financial advisor doesn’t replace your estate planning attorney, but they play a critical coordinating role. They ensure your beneficiary designations align with your estate plan, review titling of assets for consistency with your trust structure, and model how various gifting strategies interact with your overall financial picture.
With the federal estate tax exemption now permanently set at $15 million per individual ($30 million per married couple) under the One Big Beautiful Bill Act, the estate planning conversation for many high-net-worth families has shifted from exemption urgency to thoughtful, durable strategy — dynasty trusts, step-up in basis optimization, and state-level estate tax considerations for clients in states that maintain their own estate taxes.
Risk Management and Insurance Analysis
Wealth preservation is as important as wealth growth. A comprehensive advisor reviews your insurance coverage — life, disability, liability, and long-term care — to identify gaps or redundancies relative to your current net worth. For high-net-worth clients, strategies like private placement life insurance (PPLI) may be relevant tools worth evaluating alongside your attorney and tax advisor.
How a Full-Service Financial Advisor Differs From a Broker
The distinction matters enormously for families with significant assets. Here is a direct comparison of how these models differ across the dimensions that matter most.
| Dimension | Full-Service Financial Advisor | Product-Focused Broker |
|---|---|---|
| Compensation structure | Advisory fee (assets under management or flat retainer); insurance commissions disclosed separately | Primarily commissions from product sales |
| Legal standard | Fiduciary when providing investment-advisory services | Suitability or Reg BI (best interest) standard |
| Scope of guidance | Investments, taxes, estate, retirement income, risk — integrated | Primarily investment products; limited holistic planning |
| Relationship model | Ongoing, year-round advisory relationship | Transactional; often reactive |
| Transparency | Written fee disclosure; ADV document required | Compensation often embedded in product costs |
| Best suited for | High-net-worth families with complex, multi-dimensional planning needs | Simpler investment needs; smaller portfolios |
The SEC’s investor education resources provide additional guidance on the distinction between investment advisers and broker-dealers.
Why High-Net-Worth Families Need a Full-Service Financial Advisor
Mass-market financial planning tools and generalist brokers are built for typical investors — people accumulating toward retirement with relatively straightforward circumstances. High-net-worth families face a fundamentally different set of challenges that require a different caliber of guidance.
The Complexity Gap: What Changes Above $500K in Investable Assets
Once your investable assets cross meaningful thresholds, your financial decisions become significantly more interconnected. Consider what a typical HNW client manages simultaneously:
- A taxable brokerage account with appreciated positions and embedded capital gains
- Multiple tax-advantaged accounts (traditional 401(k), Roth IRA, SEP IRA, or defined benefit plan)
- Employer stock compensation (RSUs, options, or ESPP)
- A trust or family LLC structure
- Business ownership interests
- Real estate holdings
- Life insurance policies as part of estate or income-replacement strategy
Each of these components interacts with the others. A distribution from a traditional IRA to fund a home purchase affects your tax bracket, your IRMAA calculation two years forward, and the amount you should consider converting to Roth. A generic advisor or digital platform cannot model these interactions the way a full-service financial advisor can.
Tax Efficiency at Scale
For investors at the mass market, basic tax guidance is often sufficient. For a family with $3 million in investable assets and $500,000 or more in annual income, the difference between thoughtful and thoughtless tax planning can be substantial year after year.
A full-service financial advisor coordinates with your CPA to ensure your investment decisions don’t create unexpected tax consequences — and that tax planning opportunities are identified proactively rather than discovered after the fact. As Kiplinger’s tax planning resources note, year-round tax strategy rather than year-end scrambling is the hallmark of sophisticated financial planning.
Estate Planning Integration for the Permanently Changed Landscape
With the federal estate exemption now permanent at $15 million per individual, many families have moved from crisis-mode estate planning to thoughtful, long-horizon strategy. But that doesn’t mean estate planning is less important — it means it can be done deliberately, without artificial urgency.
A full-service financial advisor helps coordinate the ongoing work: reviewing trust funding, ensuring beneficiary designations are updated after life events, modeling multi-generational gifting strategies, and understanding how state estate taxes (which vary significantly from the federal rules) may still apply to your situation.
Behavioral Guidance During Market Volatility
Research from Morningstar’s annual “Mind the Gap” study consistently shows that investors underperform the very funds they invest in because of poor timing decisions — buying high, selling low, or abandoning their strategy during turbulence.
A full-service financial advisor provides a critical steadying influence during market dislocations. For high-net-worth clients, the stakes of an emotional decision are proportionally higher — a reactive portfolio move on a $5 million account has far greater consequences than the same percentage move on a $50,000 account.
What to Look For in a Full-Service Financial Advisor
Fiduciary Status When Providing Investment-Advisory Services
Confirm that the advisor is a registered investment adviser — meaning they act as a fiduciary when providing investment-advisory services. This is a legal standard, not just marketing language. Ask directly: “Are you a fiduciary when managing my investments?” and get it in writing through their Form ADV.
Transparent Fee Structure
A reputable full-service financial advisor will clearly explain how they are compensated — advisory fees, any potential commissions on insurance or annuity products, and any other forms of compensation. Ask for a written fee disclosure before engaging. NerdWallet’s advisor selection guide provides a useful framework for evaluating fee transparency.
Comprehensive Planning Capabilities
Not every firm calling itself a “full-service” provider actually delivers on the full breadth of services. Ask specifically about their tax planning process, how they coordinate with estate planning attorneys, and how they handle concentrated stock or business sale situations. These are the scenarios where a true full-service financial advisor demonstrates their value.
A Team With Deep Experience
For complex wealth situations, you want an advisor backed by a capable team. Ask about credentials — CFP®, CFA®, CPA/PFS — and how the firm handles situations that require specialist input.
Davies Wealth Management: Full-Service Advising for HNW Families
At Davies Wealth Management, we provide comprehensive wealth management services designed specifically for high-net-worth individuals, executives, professional athletes, and business owners in Stuart, Florida and beyond.
Our founder, Thomas Davies, brings 30 years of financial services experience — beginning in 1996 — to every client relationship. The firm was founded in 2009 and opened its Stuart office in 2018.
As a fee-based fiduciary registered investment adviser with the State of Florida, Davies Wealth Management provides investment-advisory services under a fiduciary standard. Any insurance or annuity compensation is separately disclosed. We work with clients who have a minimum of $500,000 in investable assets — because that threshold reflects the level of complexity where truly comprehensive planning delivers its greatest value.
We coordinate investments, tax strategy, retirement income planning, estate plan alignment, and risk management as an integrated whole — not as separate silos. In my experience working with clients who have outgrown their previous advisor or national brokerage firm, the missing ingredient is almost always coordination: having one trusted professional who understands how every financial decision affects every other part of the picture.
Free Download
The Complete Florida Retirement Guide
A comprehensive, plain-English guide to retirement planning in Florida — income strategies, tax considerations, Social Security timing, and healthcare planning for Treasure Coast retirees.
Frequently Asked Questions About Full-Service Financial Advisors
What is a full-service financial advisor, and how is it different from a broker?
A full-service financial advisor provides holistic, ongoing guidance across investments, taxes, retirement income, estate planning, and risk management under a fiduciary standard when providing investment-advisory services. A broker primarily sells investment products and is compensated through commissions, with a suitability or best-interest standard rather than a fiduciary standard for advisory services.
How does a full-service financial advisor get paid?
Full-service financial advisors typically charge an advisory fee based on assets under management or a flat retainer. Some advisors, particularly fee-based fiduciaries, may also receive disclosed commissions on specific insurance or annuity products. The compensation structure should be fully disclosed in writing before you engage.
At what level of wealth does a full-service financial advisor make sense?
The complexity that makes full-service advising most valuable typically emerges around $500,000 or more in investable assets, and grows substantially as wealth increases. Families with multi-million-dollar portfolios, business ownership, deferred compensation, or complex estate situations gain the most from integrated, comprehensive planning.
Can a full-service financial advisor replace my CPA or estate attorney?
No — and a good full-service financial advisor won’t suggest otherwise. Their role is to coordinate and integrate guidance across your entire financial picture, working alongside your CPA and estate attorney rather than replacing them. The value is in ensuring these specialists are working from the same strategic foundation.
What questions should I ask a full-service financial advisor before hiring them?
Ask whether they act as a fiduciary when providing investment-advisory services, how they are compensated, what their process is for tax planning and estate coordination, how they handle concentrated stock or business sale situations, and what their client minimum is. Request their Form ADV, which all registered investment advisers are required to provide.
Ready to Work With a Full-Service Financial Advisor?
If you’ve been managing your wealth in separate silos — one person for investments, another for insurance, your accountant reacting at year-end — you may be missing the coordinated strategy that a true full-service financial advisor provides. The families who build and preserve the most wealth over time aren’t just choosing good investments. They’re working with advisors who see the entire picture.
→ Take our Financial Wellness Quiz to see how well your current plan addresses all the dimensions of comprehensive wealth management: tdwealth.net/wellness-quiz
Or, if you’re ready to explore whether Davies Wealth Management is the right fit for your situation, we’d welcome the conversation. Book a complimentary phone call and let’s talk about where you are and where you want to go.
This post is for educational purposes only and does not constitute personalized investment, tax, or legal advice. Consult a qualified financial, tax, or legal professional for guidance specific to your situation.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply