If you're wondering about the cost of financial planning, you're asking the right question. The price of professional financial advice varies dramatically based on how you pay, what services you need, and the complexity of your financial situation.
Most people can expect to pay anywhere from $1,000 to $5,000 for a comprehensive one-time financial plan, while ongoing financial planning and investment management typically costs 0.75% to 1.5% of your assets annually. But there's much more to understand about these fee structures.
Table of Contents
- How do financial advisors charge for a financial plan?
- What is a typical AUM fee for ongoing financial planning?
- How much does a one-time comprehensive financial plan cost?
- How much is a flat annual retainer for a financial advisor?
- What do financial advisors charge per hour?
- What affects how much you pay for financial planning?
- Which financial planning fee structure is right for you?
- How do you get the most value from what you pay an advisor?
How do financial advisors charge for a financial plan?
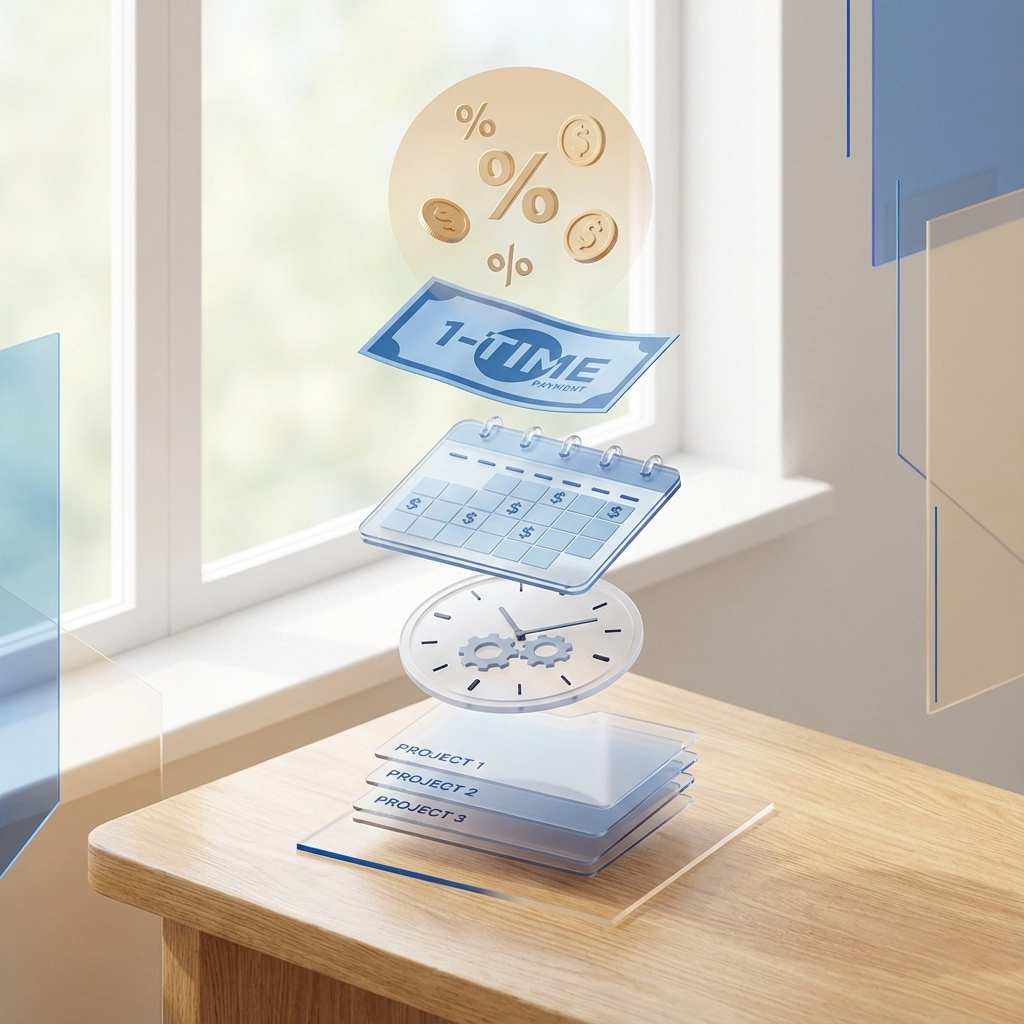
Financial advisors charge in five main ways: a percentage of the assets they manage, a one-time fee for a written plan, a flat annual retainer, an hourly rate, or a fixed project fee. Which one costs you least depends less on the headline rate than on how much ongoing work you actually need. The sections below give the going range for each.
Financial advisors typically charge for their services in five main ways. Understanding these structures helps you compare options and choose what works best for your situation and budget.
Fee-only financial advisors are often the most transparent about their pricing since they don't earn commissions from product sales. This makes them a straightforward choice if you want pricing clarity and fewer product-sales conflicts.
What is a typical AUM fee for ongoing financial planning?
Most portfolios are charged between 0.75% and 1.5% of assets per year. Portfolios between $500,000 and $1 million usually sit at 1.0% to 1.25%, and portfolios above $2 million commonly fall to 0.5% to 1.0%. Many advisors tier the rate, so the percentage drops as each band of assets is added.
The most common fee structure for ongoing financial planning and investment management is the AUM model. Here, you pay an annual percentage of the assets your advisor manages.
Typical AUM fee ranges:
- 0.75% to 1.5% annually for most portfolios
- 1.0% to 1.25% is standard for portfolios between $500,000 and $1 million
- 0.5% to 1.0% for larger portfolios over $2 million
Real-world examples:
- $500,000 portfolio = $3,750 to $7,500 annually
- $1,000,000 portfolio = $7,500 to $12,500 annually
- $2,000,000 portfolio = $10,000 to $20,000 annually
Many advisors use tiered pricing where larger portfolios pay lower percentage rates. For instance, you might pay 1.25% on the first $500,000, 1.0% on the next $500,000, and 0.75% on assets above $1 million.
AUM fees work well if you want ongoing investment management, regular portfolio rebalancing, and continuous access to your advisor for financial planning questions.
How much does a one-time comprehensive financial plan cost?
A standalone comprehensive plan generally runs $2,500 to $5,000, and the median is about $3,000. Simple plans covering basic retirement questions start near $1,500, while complex situations involving business ownership or multiple income sources run $4,000 to $6,000 or more. You pay once and implement the recommendations yourself.
If you prefer to pay once for a comprehensive financial plan rather than ongoing fees, expect to invest $2,500 to $5,000 for a thorough analysis.
What you typically receive:
- Complete analysis of your current financial situation
- Retirement planning projections
- Insurance needs assessment
- Tax optimization strategies
- Estate planning recommendations
- Investment allocation guidance
Cost breakdown by complexity:
- Simple plans: $1,500 to $3,000 (basic retirement planning, simple investment advice)
- Standard plans: $2,750 to $3,500 (comprehensive analysis for typical situations)
- Complex plans: $4,000 to $6,000+ (multiple income sources, business ownership, complex tax situations)
The median cost for a standalone financial plan is approximately $3,000, making this option attractive if you're comfortable implementing recommendations yourself or working with separate investment managers.
How much is a flat annual retainer for a financial advisor?
Flat retainers typically run $2,000 to $4,000 a year for basic planning, $4,000 to $8,000 for comprehensive planning, and $8,000 to $15,000 or more for complex high-net-worth situations. The fee does not move with your portfolio size. That makes it worth comparing when much of your wealth sits in an employer plan, real estate, or a business your advisor does not manage.
Some independent financial advisors charge fixed annual fees regardless of your asset levels. This structure can be cost-effective for high-net-worth individuals or those with complex planning needs but smaller investment portfolios.
Annual retainer ranges:
- Basic planning: $2,000 to $4,000 annually
- Comprehensive planning: $4,000 to $8,000 annually
- Complex/high-net-worth planning: $8,000 to $15,000+ annually
Retainer fees often include unlimited consultations, regular plan updates, and comprehensive financial strategy development. This model works particularly well if you have substantial assets in employer retirement plans, real estate, or other investments your advisor doesn't directly manage.
What do financial advisors charge per hour?
Hourly rates generally range from $200 to $500, with $250 the median. Advisors in major metropolitan areas are typically at the higher end. Many will also quote a fixed project fee instead, such as $1,500 to $3,000 for a retirement income analysis or $1,000 to $2,500 for an estate plan review.
For specific financial planning needs, some advisors offer hourly or project-based pricing.
Hourly rates typically range:
- $200 to $500 per hour
- $250 per hour is the median rate
- $300 to $400 per hour for CFP® professionals in major metropolitan areas
Common project-based fees:
- Retirement income analysis: $1,500 to $3,000
- Stock option planning: $2,000 to $4,000
- Estate plan review: $1,000 to $2,500
- Tax optimization strategy: $1,500 to $3,500
- Insurance needs analysis: $500 to $1,500
Hourly fees work well if you have specific questions, need a second opinion, or want guidance on a particular financial decision without committing to ongoing advisory relationship.
What affects how much you pay for financial planning?
Six things move the price: how much you have invested, how complex your situation is, where the advisor practices, what credentials they hold, how much service you want, and how often you expect to meet. Complexity and service level usually matter more than portfolio size. Each is covered below.
Several key factors influence how much you'll pay for financial planning services:
Asset levels: Larger portfolios often qualify for reduced percentage fees, though total dollar costs increase.
Complexity: Multiple income sources, business ownership, complex tax situations, or significant estate planning needs typically increase costs.
Geographic location: Advisors in major metropolitan areas like New York, San Francisco, or Miami generally charge higher fees than those in smaller markets.
Advisor credentials: CFP® professionals, CPAs, or advisors with advanced degrees often command higher fees due to their specialized expertise.
Service level: Comprehensive financial planning with regular meetings and unlimited access costs more than basic investment management or limited planning services.
Frequency of communication: Some advisors charge more for clients who require frequent meetings or extensive hand-holding.
Which financial planning fee structure is right for you?
Choose the assets-under-management model if you want continuous investment management and regular contact. Choose a one-time plan if you mainly need a roadmap and are comfortable acting on it yourself. A flat retainer suits complex planning needs alongside smaller investable assets, and hourly pricing suits a specific question or a second opinion.
Your ideal fee structure depends on your specific needs and preferences:
Choose AUM fees if:
- You want ongoing investment management
- You prefer regular portfolio monitoring and rebalancing
- You value continuous access to your advisor
- Your situation changes frequently
Choose one-time planning if:
- You're comfortable implementing recommendations yourself
- You primarily need a roadmap rather than ongoing guidance
- You have investment management handled elsewhere
- Cost minimization is your priority
Choose retainer fees if:
- You have complex planning needs but smaller investable assets
- You want comprehensive planning without asset-based fees
- Your wealth is tied up in non-liquid investments
- You prefer predictable annual costs
Choose hourly fees if:
- You have specific, limited questions
- You want a second opinion on existing plans
- You need guidance on a particular decision
- You prefer paying only for services used
How do you get the most value from what you pay an advisor?
Verify credentials and check the advisor’s background through a regulatory database before you sign anything. Get in writing exactly which services are included, how often you will meet, and what falls outside the fee. Then compare advisors on total dollar cost rather than headline percentage, and ask directly how the advisor is compensated and what conflicts that creates.
To ensure you receive good value for your financial planning investment:
Research credentials: Look for CFP® certification, relevant experience, and positive client reviews. Check advisors' backgrounds through FINRA's BrokerCheck database.
Understand what's included: Clarify exactly what services you'll receive, how often you'll meet, and what ongoing support is provided.
Compare total costs: Don't focus solely on percentage rates. Calculate actual dollar amounts and compare what you're getting for those fees.
Ask about conflicts of interest: Fee-only financial advisors typically have fewer conflicts than commission-based advisors who earn money from product sales.
Review performance expectations: Understand how your advisor will measure success and what benchmarks they use.
For more insights on financial planning strategies and market perspectives, check out our weekly discussions on The 1715 Capital Forum podcast, where we dive deep into wealth management topics that matter to investors.
According to NerdWallet's research, the average investor working with a financial advisor sees improved portfolio performance that often exceeds the advisory fees paid, particularly when factoring in behavioral coaching and tax optimization strategies.
The key is finding an advisor whose fee structure aligns with your needs and whose expertise justifies the cost. Whether you choose ongoing management or one-time planning, professional financial guidance can provide significant value when it helps you avoid costly mistakes, optimize your tax strategy, and stay disciplined during market volatility.
Ready to explore your financial planning options? Consider your current situation, determine what level of ongoing support you need, and contact our team to discuss which approach might work best for your specific goals and circumstances.
This content is for educational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Advisory services offered through Davies Wealth Management, a Registered Investment Adviser. Please consult a qualified financial, tax, or legal professional regarding your specific situation.
Leave a Reply