A strong cashflow investment strategy is the foundation of a retirement that actually works — one where income arrives predictably, taxes don’t erode every distribution, and the portfolio still grows enough to outpace thirty years of inflation. For high-net-worth retirees with $1M to $10M or more in investable assets, that balance is achievable, but it requires a fundamentally different approach than what mass-market investors typically use.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
Most retirement income advice is built around the 4% rule and a simple stock-bond mix. That framework was designed for median-wealth households. It doesn’t account for concentrated stock positions, alternative asset access, tax bracket management across seven figures of income, or the estate planning dimension that affects every distribution decision in a large portfolio.
This guide walks through five strategies that address all of those dimensions — and explains why the difference between getting this right and getting it wrong compounds dramatically over a multi-decade retirement.
Why Cashflow Investment Strategy Matters More at High Net Worth
The Retirement Income Problem Is Different When Assets Are Large
A retiree with $500,000 invested faces one primary risk: running out of money. A retiree with $5,000,000 faces a layered set of problems: IRMAA surcharges on Medicare premiums, the net investment income tax (NIIT) on passive income, required minimum distributions that push taxable income higher than desired, and potential estate tax exposure at the state level — even with the federal exemption now permanently set at $15,000,000 per individual under the One Big Beautiful Bill Act.
Each of those problems can cost tens of thousands of dollars annually if ignored. The right cashflow investment architecture anticipates them all.
Why Mass-Market Income Strategies Fall Short
Standard retirement income advice — put 60% in stocks, 40% in bonds, withdraw 4% — works tolerably for portfolios under $500,000. It leaves significant value on the table for portfolios above that threshold.
Consider the comparison:
| Factor | Mass-Market Approach | HNW Cashflow Investment Approach |
|---|---|---|
| Income sources | Dividends, bond interest, portfolio withdrawals | Dividends, bond ladders, rental income, private credit, option overlays, annuity income floors |
| Tax efficiency | Pre-tax and Roth accounts managed separately | Coordinated Roth conversion ladders, QCD stacking, tax-loss harvesting, IRMAA bracket management |
| Growth preservation | Static asset allocation, rebalanced annually | Dynamic allocation by account type, bucket strategy, tax-aware rebalancing |
| Estate coordination | Minimal — withdrawals made as needed | Every distribution decision evaluated for estate and inheritance tax impact |
| Concentration risk | Not applicable for most clients | Charitable remainder trusts, exchange funds, staged liquidation to manage embedded gains |
The gap in after-tax income between these two approaches, on a $3M portfolio over a 25-year retirement, can easily exceed $500,000. That’s not a small optimization — it’s a material difference in lifestyle and legacy.
Strategy 1: The Income Floor — Covering Non-Negotiable Expenses First
Building a Cashflow Investment Base That Doesn’t Depend on Markets
The first principle of a sound cashflow investment strategy for high-net-worth retirees is separating income that must be reliable from income that can fluctuate. Essential expenses — housing, healthcare, travel that defines your lifestyle, support for family members — should never depend on what the market does in a given year.
Income floor sources typically include:
- Social Security — optimizing the filing strategy (often delaying to age 70 for the higher earner) is one of the highest-value decisions in retirement
- Pension income (if applicable)
- Bond ladders — short- to intermediate-term investment-grade bonds maturing in sequence, providing predictable cash at defined intervals
- Fixed annuity or SPIA income — a single premium immediate annuity converts a lump sum into a predictable monthly payment, effectively purchasing a private pension; commissions and disclosures apply and vary by product
- Required minimum distributions (RMDs) — once mandatory, these become a structural income source worth planning around rather than against
The income floor doesn’t need to cover everything — it only needs to cover enough that a 30% portfolio decline doesn’t force lifestyle changes or panic selling.
How Much Floor Is Enough?
A common benchmark: secure at least 80–100% of essential monthly expenses from predictable sources before layering in growth assets. For a household spending $15,000/month on fixed costs, that means ensuring $12,000–$15,000 arrives regardless of equity performance.
This approach, sometimes called liability-matching, is standard practice among institutional pension managers. There’s no reason individual retirees with significant assets shouldn’t use the same logic. Consult a qualified financial professional to determine the right floor structure for your specific situation.
Strategy 2: Dividend and Income Investing — Quality Over Yield
Cashflow Investment Through Dividend-Paying Equities
Dividend-focused investing often conjures images of retirees chasing high-yield stocks — a strategy that frequently backfires when those companies cut dividends in downturns. Sophisticated cashflow investment planning takes a different approach: dividend growth over current yield.
Companies that have consistently grown their dividends for 10, 20, or 30 years share common characteristics:
- Strong free cash flow generation
- Durable competitive advantages
- Management teams committed to returning capital to shareholders
- Balance sheets capable of sustaining payouts through economic cycles
A 3% dividend yield that grows at 6% annually doubles roughly every 12 years. That growth component protects purchasing power in a way that a static 6% yield from a distressed company cannot.
Tax-Efficient Dividend Cashflow Investment Positioning
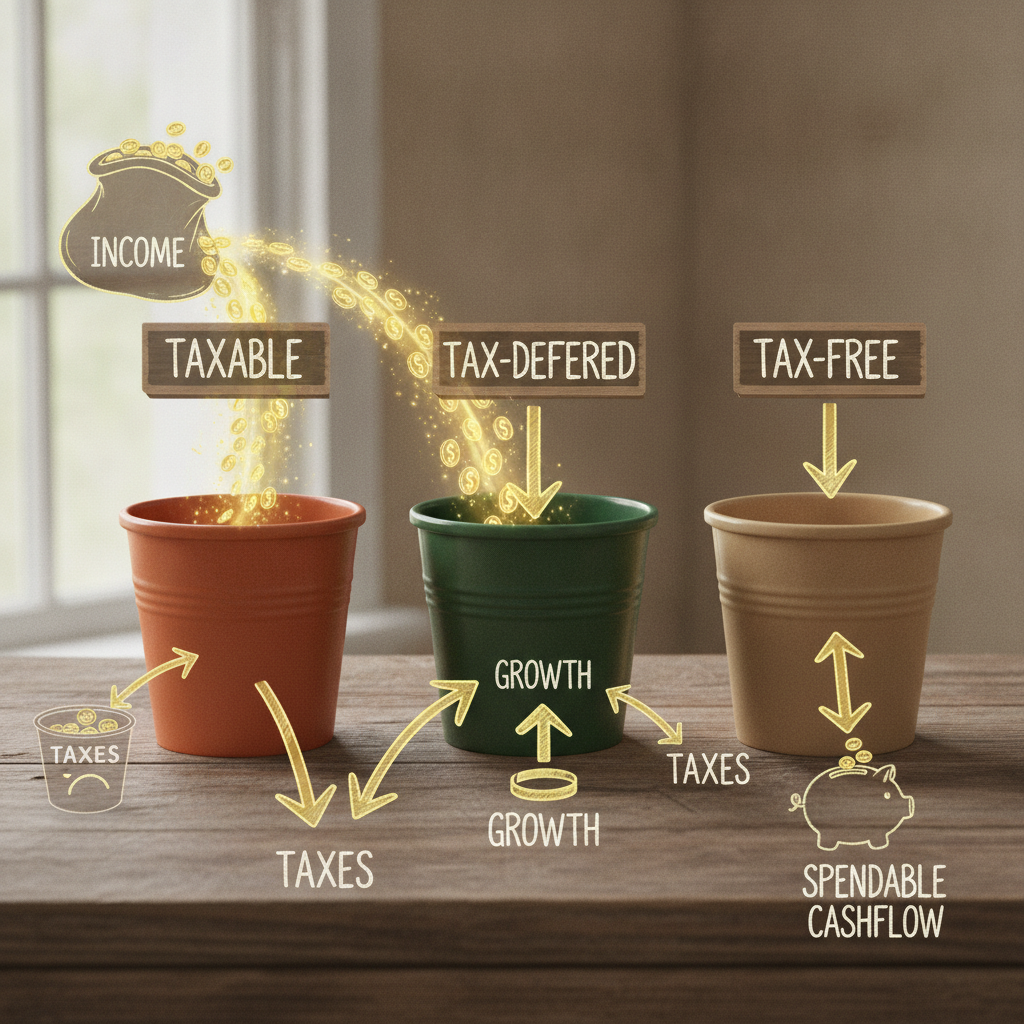
For high-net-worth investors, where dividends land in the portfolio matters as much as what dividends are earned. Qualified dividends are taxed at preferential long-term capital gains rates — but only in taxable accounts. Holding dividend-paying equities in tax-deferred accounts wastes that preference.
The general principle for tax-efficient cashflow investment positioning:
- Taxable accounts: Tax-efficient equities, qualified dividend payers, municipal bonds, index funds with low turnover
- Tax-deferred accounts (traditional IRA/401k): REITs, high-yield bonds, active strategies with higher turnover
- Tax-free accounts (Roth): Highest-growth assets, small-cap equities, alternatives with high expected return
This asset location framework — not just asset allocation — is where substantial after-tax value is created. Learn more about how comprehensive wealth management services integrate tax-efficient positioning across account types.
Strategy 3: Alternative Income Sources That Broaden Cashflow Investment
Private Credit and Income-Generating Alternatives
One advantage of high-net-worth status is access to investment structures not available to smaller portfolios. Private credit — direct lending to middle-market companies outside the public bond market — has historically offered higher yields than comparable public fixed income, with contractual income schedules.
These strategies typically require accredited investor or qualified purchaser status and often have high minimum investments. Liquidity is limited — these are not suitable for the income floor portion of a portfolio, but they can enhance the overall cashflow investment yield on a portion of a larger portfolio.
Other alternative income sources worth exploring with a qualified advisor:
- Real estate investment trusts (REITs) — public or private, providing rental income exposure without direct property management
- Business development companies (BDCs) — similar to private credit but publicly traded, with corresponding liquidity
- Infrastructure funds — toll roads, utilities, pipelines, and similar assets with long-duration contractual cash flows
- Covered call strategies — systematically selling call options against existing equity holdings to generate premium income, typically at the cost of some upside participation
The appropriate allocation to alternatives varies considerably by portfolio size, liquidity needs, time horizon, and tax situation. These strategies carry distinct risks and are not appropriate for all investors — consult a qualified financial advisor before implementation.
Rental Real Estate as a Cashflow Investment Vehicle
Many high-net-worth retirees already hold investment real estate. Structuring that ownership correctly — through LLCs, trusts, or qualified opportunity zone investments — can significantly affect both current income and eventual estate transfer.
Rental income from real estate is subject to specific passive activity rules, depreciation recapture on sale, and potential NIIT exposure. For retirees with significant real estate holdings, the interaction of these rules with Social Security income, Medicare IRMAA thresholds, and Roth conversion strategy deserves dedicated planning attention. Resources like IRS Publication 527 on Residential Rental Property provide detailed guidance on the applicable tax rules.
Strategy 4: Tax-Aware Distribution Planning — The Hidden Multiplier
Cashflow Investment Returns Are Only as Good as What You Keep
A portfolio generating $200,000 in gross annual income can produce dramatically different after-tax income depending on how distributions are structured. For high-net-worth retirees, the following tax dynamics interact simultaneously:
- Federal ordinary income tax on interest, non-qualified dividends, and traditional IRA/401k distributions
- Net investment income tax (NIIT) — an additional 3.8% on investment income above certain thresholds
- Medicare IRMAA surcharges — higher Medicare Part B and Part D premiums triggered when income crosses specific brackets; for 2026, these surcharges can add thousands of dollars annually to Medicare costs
- Capital gains rates — preferential rates of 0%, 15%, or 20% depending on income level
- State income tax — Florida’s absence of a state income tax is a material advantage for residents, particularly those receiving large RMDs or converting traditional IRA assets to Roth
Roth Conversion as a Cashflow Investment Optimization Tool
Roth conversions — moving assets from pre-tax traditional IRA accounts to tax-free Roth accounts — are one of the most powerful levers available to high-net-worth retirees in the years before RMDs begin. The logic is straightforward: pay tax at today’s known rate on a calculated amount, in exchange for eliminating future RMDs and future tax on all growth from that balance.
For a retiree with $2M in traditional IRA assets and a 20-year horizon, strategic conversions of $100,000–$200,000 per year — carefully calibrated to stay below IRMAA thresholds and avoid triggering the top marginal bracket — may reduce the taxes owed over a lifetime, depending on future tax rates and how long the money stays invested. The IRS provides detailed Roth IRA guidance on conversion rules and contribution limits.
The optimal Roth conversion amount depends on current and projected future income, anticipated tax rates, Social Security filing date, beneficiary characteristics, and other factors. Work with a qualified tax and financial planning professional to model your specific situation.
Qualified Charitable Distributions — A Cashflow Investment Tax Strategy for Philanthropic Retirees
For retirees aged 70½ or older with charitable intent, Qualified Charitable Distributions (QCDs) allow direct transfers from an IRA to a qualified charity — up to applicable annual limits — that count toward RMD satisfaction without adding to adjusted gross income.
This is significant because lower AGI directly reduces IRMAA exposure, may prevent the triggering of the NIIT, and can preserve preferential capital gains rates. For a retiree with substantial charitable giving already planned, routing that giving through QCDs is a straightforward enhancement to the cashflow investment and tax strategy. Fidelity’s QCD resource center provides useful background on mechanics and limits.
Strategy 5: Dynamic Withdrawal Sequencing and Portfolio Longevity
Cashflow Investment Withdrawal Order Affects Long-Term Wealth Significantly
The order in which you draw from different account types — taxable, tax-deferred, tax-free — materially affects how long a portfolio lasts and what passes to heirs. This is called withdrawal sequencing, and it’s where sophisticated planning diverges sharply from simple rules.
Conventional wisdom says draw from taxable accounts first, defer tax-advantaged accounts as long as possible. That heuristic is often wrong for high-net-worth retirees because:
- Letting a large traditional IRA compound untouched can create massive RMDs in later years, pushing income into the highest brackets
- A Roth account that grows tax-free for 20 additional years creates far more tax-free wealth than waiting produces
- Drawdown from taxable accounts can strategically harvest gains at 0% or 15% rates before income rises with RMDs
The Bucket Strategy in a Cashflow Investment Context
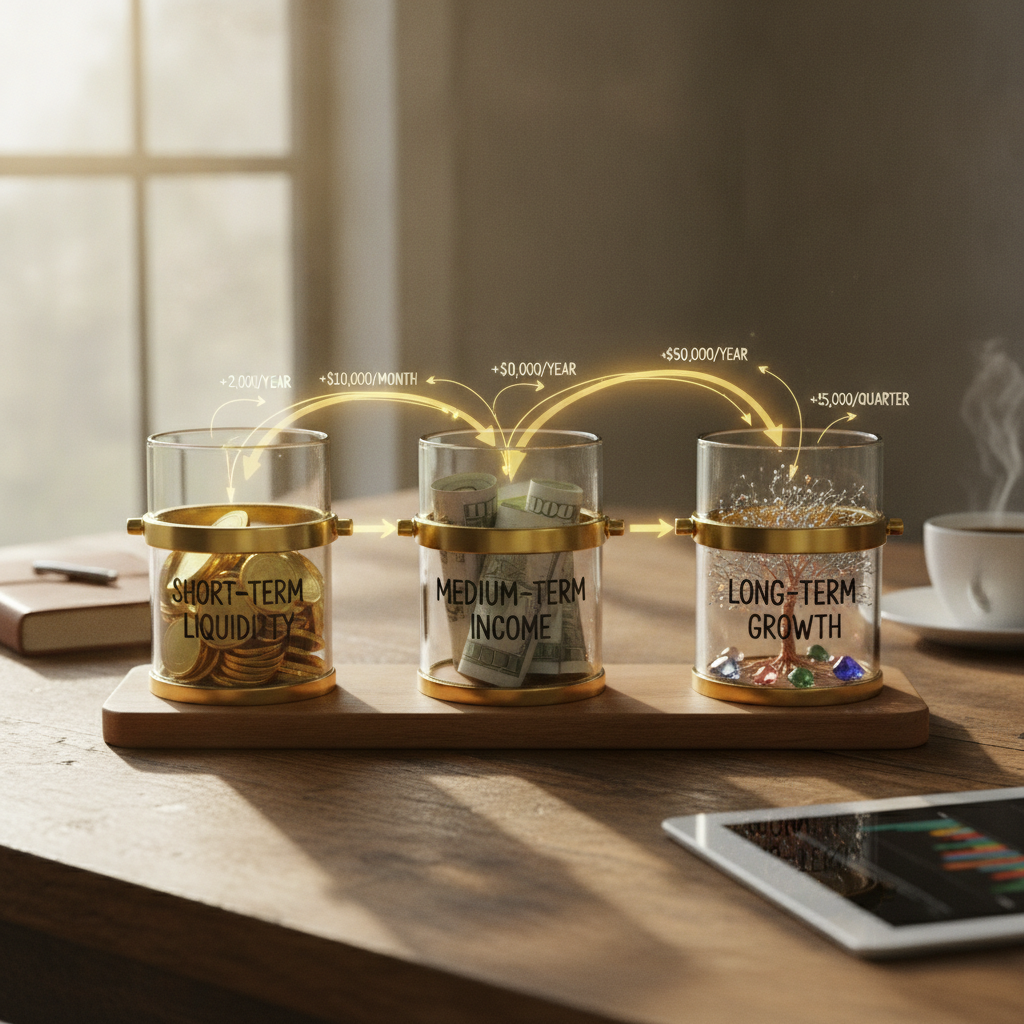
Many advisors implement a “bucket” framework for HNW retirees:
- Bucket 1 (0–2 years of expenses): Cash and short-term bonds — pure liquidity, insulates against needing to sell growth assets in down markets
- Bucket 2 (years 3–7): Intermediate fixed income, dividend equities, alternatives — moderate growth with periodic rebalancing to refill Bucket 1
- Bucket 3 (year 8+): Equities, growth alternatives, private investments — the long-duration cashflow investment engine that preserves purchasing power
The bucket approach is psychologically powerful because it makes the growth portfolio feel untouchable during downturns — because it is. Retirees who see a 25% equity decline but know their next five years of income is already secured behave very differently than those watching a single portfolio number fall.
Portfolio Longevity Planning Beyond 30 Years
Actuarial data consistently shows that couples where both spouses reach age 65 have a meaningful probability that at least one lives past 90. A 30-year retirement horizon is not unusual — a 35-year horizon is not implausible. This matters for cashflow investment planning because:
- Inflation compounding over 35 years at even 3% annually cuts purchasing power by more than half
- Healthcare costs in the final decade of life typically accelerate sharply
- Long-term care events — home health aides, assisted living, memory care — can cost $100,000 to $300,000 per year in some markets
Growth assets are not optional for most HNW retirees — they are essential to keeping pace. The cashflow investment strategy must balance present income against the real risk of outliving purchasing power. Resources like Morningstar’s retirement research provide data-driven perspective on safe withdrawal rates and portfolio longevity. For additional retirement income frameworks, Kiplinger’s retirement planning coverage offers accessible explanations of distribution strategies.
Putting It All Together: What a Coordinated Cashflow Investment Plan Looks Like
Integration Across Income, Tax, and Estate Planning
A sophisticated cashflow investment plan isn’t a single strategy — it’s a coordinated system where each decision reinforces the others. Social Security filing date affects IRMAA calculations. Roth conversion amounts affect capital gains bracket management. QCD amounts affect whether NIIT applies. RMD timing affects estate plan optimization.
This interconnectedness is why working with a fee-based fiduciary advisor — one who is compensated for advice rather than product sales, with commissions on any insurance or annuity products separately disclosed — produces materially better outcomes than managing income planning in isolation. Thomas Davies has 30 years in financial services, beginning in 1996, and the firm works with clients for whom these decisions carry real financial weight.
If you’re ready to examine how a coordinated cashflow investment strategy could work for your specific situation, consider starting with a schedule a discovery conversation with our team.
What to Expect From a Cashflow Investment Review
A comprehensive cashflow investment review for a high-net-worth retiree typically covers:
- Current income sources and projected gaps
- Tax bracket and IRMAA sensitivity analysis
- Social Security optimization modeling
- Roth conversion opportunity assessment
- Asset location review across all accounts
- Estate tax exposure at the state level (even with the permanent federal exemption, some states impose estate taxes at lower thresholds)
- Long-term care funding strategy
- Charitable giving efficiency review
No two clients look alike. A retired executive with concentrated company stock faces entirely different challenges than a business owner receiving installment sale payments or a retired physician with a defined benefit pension. The cashflow investment framework is universal; the implementation is individual.
Free Download
The Complete Florida Retirement Guide
A comprehensive, plain-English guide to retirement planning in Florida — income strategies, tax considerations, Social Security timing, and healthcare planning for Treasure Coast retirees.
Frequently Asked Questions About Cashflow Investment in Retirement
What is a cashflow investment strategy and why does it matter in retirement?
A cashflow investment strategy is a coordinated plan for generating predictable income from a portfolio while preserving the growth needed to outpace inflation over a multi-decade retirement. For high-net-worth retirees, it matters because the difference between an optimized and an unoptimized strategy can amount to hundreds of thousands of dollars in after-tax income over a 25–30 year period.
How is cashflow investment planning different for high-net-worth retirees?
High-net-worth retirees face tax exposures — IRMAA surcharges, the net investment income tax, and large required minimum distributions — that mass-market retirees rarely encounter. They also have access to income-generating alternatives, trust structures, and sophisticated tax-planning strategies that smaller portfolios cannot efficiently use. The complexity and the opportunity are both significantly greater.
Which cashflow investment sources are most tax-efficient for wealthy retirees?
Qualified dividends and long-term capital gains benefit from preferential tax rates. Qualified Charitable Distributions allow philanthropic retirees to satisfy RMDs without increasing adjusted gross income. Roth IRA distributions are entirely income-tax-free. Municipal bond interest is typically exempt from federal income tax. The most tax-efficient source depends on your specific income mix, bracket exposure, and charitable intent — consult a qualified tax professional for your situation.
Should I use annuities as part of my cashflow investment strategy?
Annuities can serve a legitimate role in the income floor portion of a cashflow investment plan, providing predictable payments that remove sequence-of-returns risk from essential expenses. However, they are not appropriate for every situation — product features, costs, and the financial strength of the issuing insurance company all require careful review. Any annuity recommendation should come with full disclosure of compensation to the advisor. Consult a qualified financial professional who is willing to explain all costs and alternatives before purchasing.
How often should a cashflow investment strategy be reviewed?
At minimum, annually — and whenever a significant life event occurs, such as a change in health status, the death of a spouse, a large inheritance, a business liquidity event, or a major tax law change. Because tax brackets, Medicare thresholds, and portfolio values all shift over time, even a well-constructed cashflow investment plan requires regular recalibration to remain optimal.
Next Steps: Building Your Cashflow Investment Plan
A retirement with reliable income, tax efficiency, and long-term growth isn’t the result of luck — it’s the result of a deliberate cashflow investment strategy built with the complexity of a large portfolio in mind. The five strategies outlined here — income floor construction, dividend growth investing, alternative income sources, tax-aware distribution planning, and dynamic withdrawal sequencing — work together as a system.
Getting them right requires coordination across investment management, tax planning, estate planning, and Medicare strategy. That’s the kind of integrated planning Davies Wealth Management provides for high-net-worth retirees and pre-retirees throughout Florida and beyond.
Take our Financial Wellness Quiz to see how your current income strategy compares to best practices for high-net-worth retirees — and identify where the most significant opportunities may lie in your specific situation.
Already know you’re ready for a deeper conversation? Book a complimentary phone call with our team. As a fee-based fiduciary investment adviser registered with the State of Florida, Davies Wealth Management is compensated for advice — with any insurance or annuity product commissions separately disclosed — so our guidance is designed around your cashflow investment goals, not a product sale.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply