
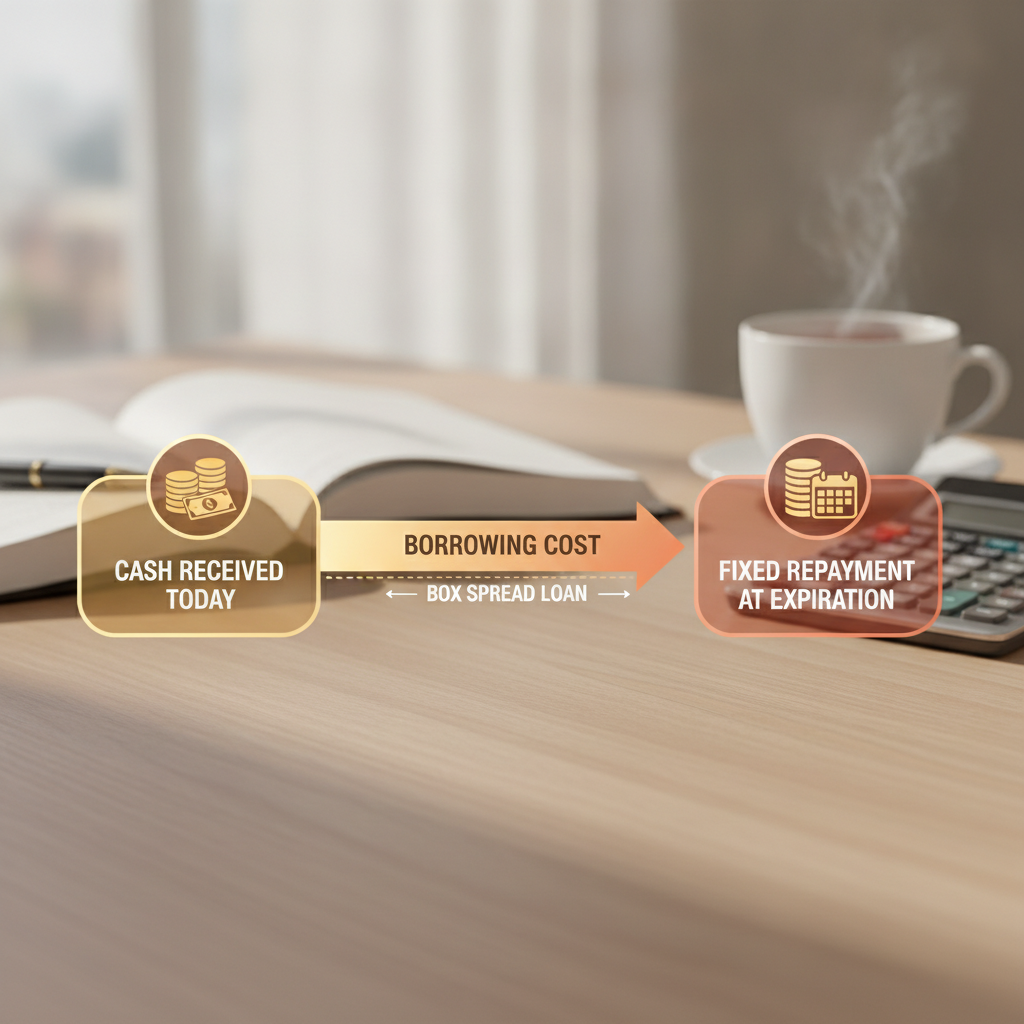
A box spread loan is a borrowing technique in which an investor sells a specific combination of four index options — a “box” — to receive cash today and repay a fixed, predetermined amount at expiration. Because the payoff is locked in by the structure of the options themselves, the borrowing cost is determined by the market, not a bank, and the rate is fixed for the term. If you have been offered or are curious about a box spread loan, this guide explains exactly how it works in plain English.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
This strategy is used almost exclusively by high-net-worth investors with margin-approved brokerage accounts and substantial portfolios. It is not a mass-market product. Understanding the mechanics, the tax rules, and the risks before you proceed is essential — and the details matter more than most people realize.
What Is a Box Spread Loan and How Does It Work?
The Basic Concept of a Box Spread Loan
A box spread is a combination of four options on the same underlying index — in this context, the S&P 500 Index (SPX) — at two different strike prices. When constructed correctly, the four options together lock in one fixed amount owed at expiration, regardless of where the index trades between now and then.
That fixed, predictable outcome is what makes it useful as a borrowing tool. You receive cash upfront from selling the box; you owe a larger fixed amount at expiration. The difference is your borrowing cost.
How the Four Options Lock In a Fixed Payoff
Here is how the structure works. Using two strike prices — call them the lower strike and the upper strike — you create four positions:
- At the lower strike: sell a call option + buy a put option
- At the upper strike: buy a call option + sell a put option
Together, these four legs always settle to the same value at expiration: the difference between the two strike prices multiplied by the contract multiplier. For SPX options, the multiplier is 100.
Hypothetical example of the mechanics only: Suppose the lower strike is 5,000 and the upper strike is 6,000. The strike width is 1,000. Multiplied by 100, the box always settles to $100,000 at expiration, no matter what the S&P 500 does. If you receive $95,000 in cash today and owe $100,000 at expiration, your borrowing cost is $5,000. The annualized rate depends on the length of the term. This is a hypothetical illustration of the mechanics only; actual execution costs, fees, and rates will differ.
Where the Rate Comes From
Unlike a bank loan or a securities-based line of credit, the borrowing rate on a box spread loan is set by competing participants in the listed options market. Sophisticated market makers, institutions, and arbitrageurs constantly trade these boxes, and their activity pushes prices toward prevailing financing rates.
The rate is fixed for the term of the box — there is no floating rate, no prime-rate adjustment. However, execution at any quoted rate is not guaranteed. The options market is dynamic, and the spread between bid and ask affects the actual cost you pay. Platform fees, adviser fees, and commissions add to the true cost. Always ask for the all-in APR before proceeding.
What Makes SPX Options Specifically Suitable
Box spread loans are built using SPX options — options on the S&P 500 Index traded on the Cboe Options Exchange. Two features of SPX options make them well-suited for this structure:
- European-style exercise: SPX options can only be exercised at expiration, not before. This eliminates the risk of early assignment disrupting your position mid-term. (Cboe SPX Options Overview)
- Cash settlement: At expiration, SPX options settle in cash — no shares of stock change hands. The fixed settlement amount flows directly between accounts.
These two features together mean that the payoff at expiration is predictable and automatic, which is what makes the box spread work as a financing tool.
How a Box Spread Loan Differs From a Margin Loan or Securities-Based Line of Credit
The Rate Structure Difference
Most portfolio-backed borrowing — margin loans, securities-based lines of credit (SBLOCs) — carries a variable interest rate that moves with short-term benchmarks. When rates rise, your borrowing cost rises with them.
A box spread loan offers a fixed rate for the term, determined at the time you execute the trade. If you need certainty about your borrowing cost over a defined period — say, 12 to 24 months — the fixed structure can be appealing. That said, the rate you receive depends on market conditions at execution, and there is no guarantee that the market rate will be favorable at any given time.
How Collateral and Margin Work
A box spread loan does not involve a lender in the traditional sense. Instead, your brokerage custodian sets aside the amount you will owe at expiration as a margin requirement. This reduces your available borrowing capacity within the account.
If the value of your portfolio falls, the custodian may issue a margin call — a demand to deposit additional funds or securities. If you cannot meet the margin call, the custodian can liquidate positions in your account to cover the obligation. This is the primary risk of a box spread loan, and it is the same fundamental risk that applies to any form of portfolio-backed borrowing.
What Happens at Expiration
On the expiration date, the box settles. You have two choices:
- Repay from cash: Have sufficient cash or liquid assets in your account to cover the settlement amount.
- Roll the box: Enter into a new box spread loan at whatever rates prevail at that time. This is essentially refinancing — and introduces rate risk. If borrowing rates have risen since you opened the original box, the new loan will cost more.
Planning for the expiration date — well in advance — is a critical part of using this strategy responsibly.
The Tax Treatment of a Box Spread Loan Under Section 1256
This is where many investors are surprised — and where working with a CPA is not optional.
SPX Options Are Section 1256 Contracts
SPX options are nonequity options, and as such they are classified as Section 1256 contracts under the Internal Revenue Code. Specifically, 26 U.S.C. §1256(b) and §1256(g)(3) define the scope of these contracts.
Two rules apply to all Section 1256 contracts:
- Mark-to-market at year end (§1256(a)(1)): Even if the box is still open on December 31, you recognize gain or loss based on the fair market value of the contracts at year end. If your box spans two calendar years, part of the borrowing cost is recognized in each year.
- 60/40 treatment (§1256(a)(3)): Gain or loss on Section 1256 contracts is treated as 60% long-term capital gain/loss and 40% short-term capital gain/loss, regardless of how long the position was actually held.
The Borrowing Cost Is a Capital Loss, Not Deductible Interest
This distinction is critical. The cost of borrowing through a box spread loan generally appears on your tax return as a capital loss — not as investment interest expense. That means:
- The tax value of the loss depends entirely on whether you have capital gains to offset.
- If you do not have sufficient capital gains, the loss does not translate into a deduction at ordinary income rates.
- Net capital losses can only offset ordinary income up to $3,000 per year ($1,500 for married filing separately) under 26 U.S.C. §1211(b). Excess losses carry forward.
Consult a qualified CPA for your specific situation before assuming any tax benefit from this strategy.
The Section 1256 Loss Carryback Election
There is one notable tax provision available to individuals: under 26 U.S.C. §1212(c), an individual may elect to carry a net Section 1256 contracts loss back three years. However:
- The carryback applies only against prior Section 1256 gains — not against other capital gains or ordinary income.
- This election is not available to estates or trusts.
- It is an election, not automatic — proper filing is required.
For investors with significant prior Section 1256 gains, this carryback can be meaningful. For those without such a history, it offers little benefit. For detailed rules on Section 1256 treatment, see IRS Publication 550.
How Year-End Mark-to-Market Affects Multi-Year Boxes
If you open a box spread loan that spans December 31, the mark-to-market rule splits the economic cost across two tax years. You may recognize a portion of the borrowing cost in the year the box is opened, and the remainder in the year it expires. This creates a timing mismatch that requires careful planning — particularly if your capital gain situation differs between the two years.
The Real Risks of a Box Spread Loan
Margin Calls and Forced Liquidation
The most significant risk is the same one that applies to any margin-based borrowing: if your portfolio value declines, your custodian can require you to deposit additional assets or liquidate positions. In a severe or rapid market downturn, this can happen quickly and at the worst possible time.
Investors with highly concentrated positions or portfolios that could experience correlated drawdowns face amplified risk here. Maintaining a substantial margin cushion — the difference between your portfolio value and the amount you owe — is critical.
Refinancing Risk at Expiration
If you plan to roll the box at expiration, you are exposed to whatever borrowing rates prevail at that time. The fixed rate you locked in today does not carry forward. If market rates have risen significantly, the renewal cost may be considerably higher than anticipated.
Execution Risk
The all-in cost of a box spread loan is not simply the difference between what you receive today and what you owe at expiration. Platform fees, commissions, and bid-ask spreads all add to the true cost. The rate implied by a quoted box may look attractive; the executed rate, after all costs, may be less so. Always request and review the full cost disclosure before executing.
Tax Complexity and Planning Risk
The Section 1256 treatment described above introduces real planning complexity. If the capital loss generated by the box does not offset capital gains in the same tax year, its value is limited: only $3,000 a year can offset ordinary income, and the rest carries forward to future years. For investors who rely on a presumed tax benefit that does not materialize, the effective after-tax borrowing cost is higher than expected.
Questions to Ask Before Using a Box Spread Loan
Key Due Diligence Questions
If someone has offered you a box spread loan — or if you are considering pursuing one — these are the questions that matter:
- What is the all-in APR, including all fees and commissions? The implied rate from the box alone is not the full picture.
- What is the exact expiration date, and how will you fund the settlement? Do you have cash or will you roll? What is your plan if rates have risen?
- What is your current margin cushion, and how large a portfolio decline could you absorb before a margin call?
- Do you have capital gains available this year to absorb the resulting Section 1256 loss? If not, what is the realistic tax benefit?
- How will the borrowing cost be reported on your tax return? Will it appear as a capital loss? Has your CPA reviewed the structure?
- If the box spans December 31, how does year-end mark-to-market affect your tax situation in each year?
- What happens to your portfolio strategy if you must liquidate positions to meet a margin call? Does this create additional taxable events?
How High-Net-Worth Investors Should Think About Box Spread Loans
The Right Context for This Strategy
A box spread loan is not a strategy for every investor, and it is not a simple substitute for a margin loan or line of credit. It is a sophisticated financing tool with a specific structure, specific tax rules, and specific risks that require active management.
For high-net-worth investors with significant capital gains to harvest, a need for short-term liquidity without selling appreciated assets, and the capacity to absorb margin risk, a box spread loan may be worth evaluating. The fixed rate structure and the 60/40 capital loss treatment under Section 1256 can be advantageous in the right circumstances.
But the keyword is circumstances. The strategy needs to fit your overall portfolio, your tax situation, and your liquidity plan. Reviewing it in isolation, without integrating it into a comprehensive financial plan, is how costly mistakes happen.
How This Fits Into a Broader Wealth Strategy
At Davies Wealth Management, we work with investors whose portfolios and financial lives are complex enough to require strategies like these to be evaluated carefully — not promoted universally. A box spread loan is one tool among many for managing liquidity and financing needs without triggering unnecessary taxable events.
The investors who benefit most from sophisticated borrowing strategies are typically those who have already optimized the fundamentals: asset location, tax-loss harvesting, Roth conversion ladders, and estate planning. If you are still in the earlier stages of that work, that is where leverage and liquidity strategies need to fit — not the other way around.
Our comprehensive wealth management services are designed for investors with $500,000 or more in investable assets who need strategies that go well beyond what a standard brokerage relationship provides. If you are evaluating a box spread loan, it is worth having that conversation in the context of your full financial picture.
If you have questions about whether a box spread loan makes sense for your situation — or simply want a second opinion on a proposal you have received — schedule a discovery conversation with our team.
Free Download
The Complete Florida Retirement Guide
A comprehensive, plain-English guide to retirement planning in Florida — income strategies, tax considerations, Social Security timing, and healthcare planning for Treasure Coast retirees.
Frequently Asked Questions About Box Spread Loans
Is a box spread loan actually a loan, or is it something else?
A box spread loan functions economically like a loan — you receive cash today and owe a fixed amount at expiration — but it is structured entirely through listed options contracts, not a credit agreement with a lender. The IRS and your brokerage treat it differently than a conventional loan, which is why understanding the Section 1256 tax rules matters before you use one.
Can I lose more than I borrowed with a box spread loan?
The options position itself is structured to have a fixed, known settlement — so the box component does not expose you to unlimited loss. The real risk is that your overall portfolio, used as margin collateral, can decline in value and trigger a margin call, potentially forcing you to sell assets at an inopportune time. The borrowing does not amplify the box itself, but it does increase your overall portfolio leverage.
How is the borrowing cost of a box spread loan taxed?
Because SPX options are Section 1256 contracts, the borrowing cost generally appears as a capital loss — 60% long-term and 40% short-term — rather than as deductible investment interest. This means the tax benefit depends on having capital gains to offset; if you do not, only $3,000 a year ($1,500 married filing separately) can offset ordinary income, and the rest carries forward. Consult a CPA for your specific situation.
What is the difference between a box spread loan and a margin loan?
A margin loan typically carries a variable interest rate tied to a benchmark, and interest is charged on your debit balance. A box spread loan has a fixed borrowing cost determined at execution by the options market, and the cost shows up as a capital loss rather than interest expense. Each has different rate structures, tax treatment, and risk profiles that need to be evaluated based on your individual circumstances.
Do I need a special account to use a box spread loan?
Yes. You need a margin-approved brokerage account with options trading authorization at an appropriate level to execute multi-leg index options strategies. Not all brokerage accounts or custodians support this structure, and minimum account sizes and approval requirements vary by custodian. Your adviser or brokerage firm can tell you whether your account qualifies.
Ready to Evaluate Whether a Box Spread Loan Fits Your Situation?
A box spread loan is a sophisticated financing strategy with real benefits in the right context — and real risks when used without a full understanding of the mechanics, the margin requirements, and the tax treatment under Section 1256.
If you have been offered a box spread loan, received a proposal you do not fully understand, or simply want an independent, fiduciary perspective on whether this strategy fits your financial plan, Davies Wealth Management is here to help.
Thomas Davies has worked in financial services since 1996, and Davies Wealth Management has served high-net-worth individuals, executives, and business owners as a fee-based fiduciary since 2009. We work with clients who have $500,000 or more in investable assets and who need advice that is built around their complete financial picture — not a single product or strategy.
Take our Financial Wellness Quiz to see how well your current financial plan addresses borrowing strategy, tax efficiency, and portfolio risk: Take the Financial Wellness Quiz →
Or if you are ready to talk now: Book a complimentary, no-obligation phone call with our team. We will listen first and answer your questions without pressure.
This post is for educational purposes only and does not constitute investment, tax, or legal advice. Consult a qualified financial adviser, CPA, and attorney for guidance specific to your situation. Davies Wealth Management is a fee-based fiduciary and investment adviser registered with the State of Florida. Insurance and annuity commissions are separately disclosed.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply