If you’re a retiree with a seven-figure portfolio, the question of the best ways to invest money short term deserves far more attention than most generic financial advice gives it. What should you do with the $150,000 to $400,000 you know you’ll need over the next 6 to 24 months—the funds earmarked for living expenses, a planned property purchase, or a gifting strategy? Where you park that money has real consequences for your after-tax yield, your Medicare premiums, and your long-term wealth.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
This is not a conversation about emergency funds for the average American. It’s a conversation about how high-net-worth retirees—those with $1 million or more in investable assets—can structure short-term cash intelligently, coordinated with their tax situation and income plan. We’ll cover six specific strategies, explain how to layer them into a cash ladder, and flag the tax traps that catch too many affluent retirees by surprise.
Why Short-Term Cash Management Matters More Than You Think
Most mass-market financial guidance treats the cash question as straightforward: keep three to six months of expenses somewhere accessible and move on. For a household spending $15,000 to $20,000 per month in retirement, that translates to holding $90,000 to $120,000 in liquid reserves. At that scale—and especially at higher balances—where you hold it and how it’s structured becomes genuinely consequential.
The Sequence-of-Returns Risk Connection
Many high-net-worth retirees intentionally maintain a larger short-term cash buffer than common rules suggest. The reason is sequence-of-returns risk: if your equity portfolio falls 25% in the early years of retirement, you don’t want to be forced to sell depressed assets just to pay living expenses. A deliberate 12- to 24-month cash cushion gives your portfolio time to recover without permanent impairment.
The critical insight here is that this buffer should be earning something. A $300,000 position sitting in a low-interest checking account earning effectively zero is one of the most avoidable and costly mistakes in retirement income planning. The best ways to invest money short term all share one defining feature: they protect your principal while generating a competitive current return.
How HNW Retirees Approach Short-Term Cash Differently
Here is where the planning truly diverges from mass-market advice. For a retiree with $2 million or more in assets, short-term cash decisions carry dimensions that simply don’t exist for the average investor:
- Tax bracket friction is significant. Interest from savings accounts, CDs and most bonds is taxed as ordinary income. The gross yield on a savings account or CD tells you very little about what you actually keep.
- IRMAA exposure is real and often underestimated. Medicare’s income-related premium surcharges are triggered by modified adjusted gross income—and interest from savings accounts, CDs, and most bond funds counts directly toward that figure.
- Institutional fund access opens better options. Investors with balances above certain thresholds often qualify for institutional share classes of money market funds with meaningfully lower expense ratios.
- Short-term cash must coordinate with the broader income plan. Which accounts you draw from, in what order, and at what level of taxable income all intersect with your short-term cash choices.
By contrast, most mass-market investors don’t face IRMAA thresholds, are in lower tax brackets, and genuinely benefit from the simplest possible approach. The best ways to invest money short term for a high-net-worth retiree require a different framework entirely.
The 6 Best Ways to Invest Money Short Term in 2026
Each option below is suited for the 6 to 24 month time horizon and treats capital preservation as the primary objective. We’ll discuss the specific tradeoffs that matter most for affluent retirees.
1. High-Yield Savings Accounts and Money Market Deposit Accounts
High-yield savings accounts offered by online banks and credit unions represent the simplest, most accessible entry point for short-term cash. They are FDIC-insured (up to applicable limits), fully liquid, and have historically offered rates meaningfully above national average savings accounts. For investors holding amounts above FDIC insurance limits, accounts can be spread across multiple institutions to extend coverage.
The primary drawback for high-net-worth retirees is straightforward: interest income is fully taxable at ordinary income rates. For someone in a top federal bracket, that erodes the effective yield substantially. High-yield savings accounts are best used for the most liquid tier of a structured cash reserve—money that might be needed within the next 60 to 90 days—rather than for the full 6 to 24 month position.
2. Treasury Bills and Short-Duration Treasuries
Treasury bills (T-bills) are among the strongest short-term investment options for high-net-worth retirees who want both safety and tax efficiency. They are direct obligations of the U.S. government, available in maturities from four weeks to 52 weeks, and offer a compelling feature that savings accounts do not: their interest income is exempt from state and local income taxes.
For a Florida retiree, the state tax exemption is less impactful because Florida levies no state income tax. But for clients with ties to higher-tax states, or for those managing income across multiple state jurisdictions, the advantage is meaningful. T-bills can be purchased directly through major brokerage platforms like Fidelity or directly from the U.S. Treasury. For the 12 to 24 month portion of your cash reserve, short-duration Treasury notes provide a natural extension of the T-bill approach with slightly longer maturities and potentially higher yields.
3. Certificates of Deposit and CD Ladders
Certificates of deposit offer a fixed interest rate for a defined term, typically ranging from three months to five years. For a retiree who knows they’ll need $150,000 in 12 months, locking that amount into a 12-month CD provides predictability and often a rate advantage over savings accounts. The tradeoff is reduced flexibility: early withdrawal typically triggers a penalty, so CDs are best reserved for funds you’re highly confident you won’t need before maturity.
The more sophisticated HNW approach is a CD ladder: dividing your short-term reserves across multiple CDs maturing at staggered intervals. For example, splitting $400,000 into four $100,000 CDs maturing at 6, 9, 12, and 18 months creates a self-replenishing structure with regular liquidity events. You can research current CD rates across FDIC-insured institutions at NerdWallet to benchmark competitive offerings. This is one of the genuinely best ways to invest money short term when you have defined, predictable cash needs on a known schedule.
4. Money Market Mutual Funds
Money market mutual funds are investment products—not to be confused with FDIC-insured money market deposit accounts at banks. They hold portfolios of short-term, high-quality debt instruments and typically aim to maintain a stable $1.00 net asset value, though this is not guaranteed and not insured by the federal government.
For high-net-worth investors, money market mutual funds offer several meaningful advantages:
- Generally higher yields than bank savings products in most market environments
- High liquidity—typically settling next business day
- Available in government, Treasury, and tax-exempt municipal varieties, allowing tax optimization
- Institutional share classes (often available at $1 million or higher minimums) carry lower expense ratios, improving net yield
Government and Treasury money market funds may offer state tax exclusions on the portion of income attributable to U.S. government securities—another edge for investors in higher state tax brackets. This category consistently ranks among the best ways to invest money short term when flexibility and liquidity are priorities.
5. Short-Term Municipal Bonds and Tax-Exempt Money Market Funds
For retirees in the top federal income tax bracket, tax-exempt municipal bonds and municipal money market funds deserve serious attention as best ways to invest money short term. Municipal bond interest is generally exempt from federal income tax, and when the issuing entity is in your state of residence, the interest may also be exempt from state income tax.
The relevant metric is the tax-equivalent yield: the taxable yield that would need to be offered to match what a tax-exempt instrument provides after taxes. At higher marginal rates, this comparison increasingly favors municipal instruments—sometimes dramatically. A qualified tax professional can calculate whether tax-exempt short-term options make sense given your specific bracket and income mix. Consult a qualified tax professional for advice tailored to your situation before selecting between taxable and tax-exempt vehicles.
6. Short-Term Bond Funds
Short-term investment-grade bond funds—those with average maturities of one to three years—occupy the outer edge of a 6 to 24 month cash strategy. They generally offer more yield potential than pure money market options in most rate environments, but come with modest price fluctuation. In a rising interest rate environment, short-term bond funds can deliver negative returns over shorter periods, which makes them unsuitable for funds needed in less than 12 months.
Floating rate funds, which hold instruments whose yields adjust periodically with prevailing rates, can also play a role when rate uncertainty is high. However, floating rate loans typically carry more credit risk than Treasury instruments. Both short-term bond funds and floating rate options are better suited for the outermost tier of a structured cash reserve—the 18 to 24 month layer—not for funds needed immediately. Consult a qualified financial professional before incorporating these into your short-term investment strategy.
Building a Cash Ladder: The Structured HNW Approach
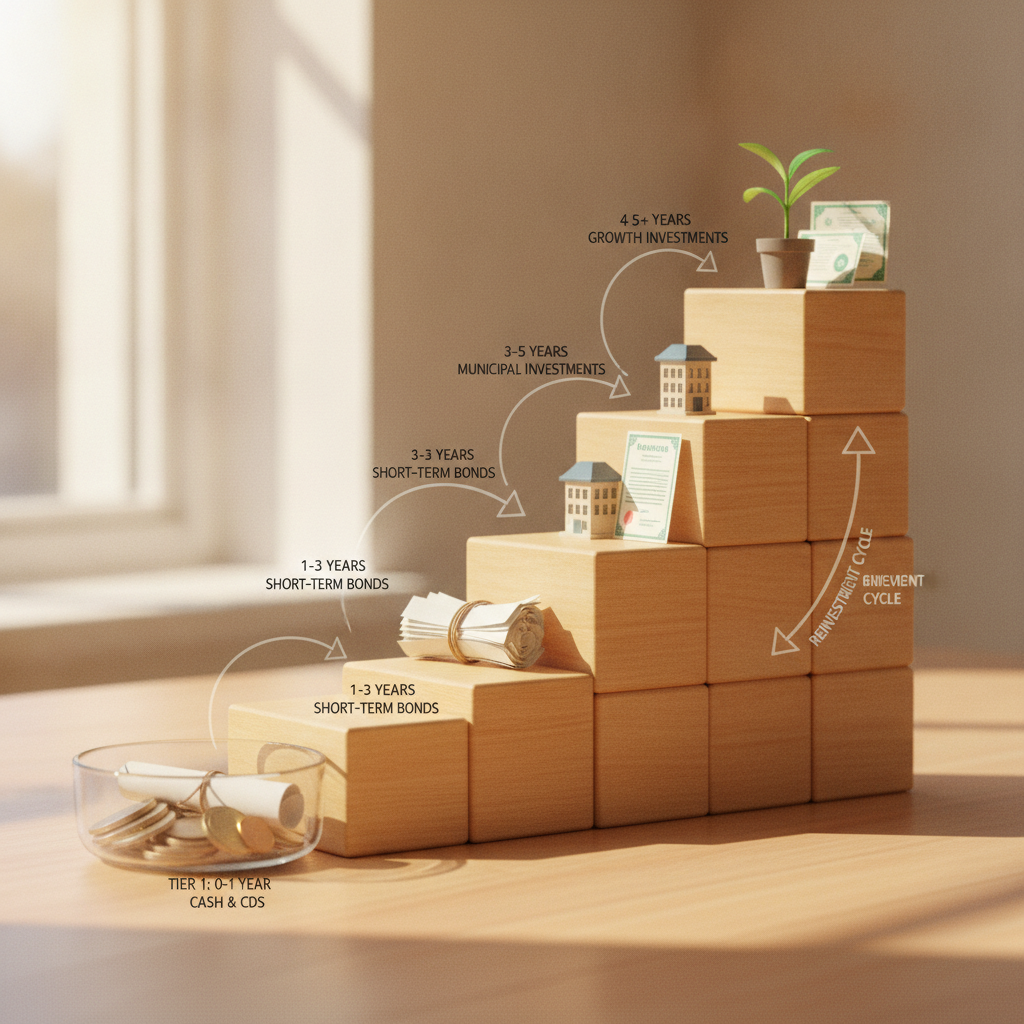
Rather than selecting a single option, most high-net-worth retirees benefit from a layered structure—often called a cash ladder—that matches the maturity of each position to the expected timing of each cash need. This approach maximizes yield while preserving liquidity at each stage of the 6 to 24 month horizon. It is, in practice, how sophisticated retirees bring together all six of the best ways to invest money short term into one coherent plan.
What Is a Cash Ladder and Why It Works
A cash ladder divides your short-term reserves into three or four tiers, each with a different purpose and maturity. Here’s how a $600,000 short-term reserve might be structured for a retiree drawing $25,000 per month from their portfolio:
- Tier 1 — Immediate (0–3 months): $150,000 in a government money market fund or high-yield savings account. Maximum liquidity, no penalty for access at any time.
- Tier 2 — Near-Term (3–9 months): $150,000 in T-bills or a 6-month CD. Earns more than Tier 1 with still-predictable returns.
- Tier 3 — Mid-Range (9–18 months): $150,000 in a 12-month CD ladder or short-duration Treasury notes. Higher expected yield with a defined maturity.
- Tier 4 — Extended (18–24 months): $150,000 in a short-term bond fund or a mix of 18- and 24-month CDs. Highest expected yield within the short-term range.
As Tier 1 depletes, proceeds from Tier 2 mature and replenish it. The result is a self-renewing structure with no single point of illiquidity, and no portion of the reserve sitting idle at below-market rates.
How Much Should You Hold in Short-Term Cash?
A practical framework for retirees in the distribution phase: hold 12 to 24 months of expected net portfolio withdrawals in stable short-term investments. If you draw $120,000 per year from your portfolio after Social Security and pension income, that points to a $120,000 to $240,000 short-term reserve. The larger end of that range is appropriate if you anticipate lumpy near-term expenses—a home purchase, a major gifting event, a business-related obligation, or a healthcare cost.
Higher reserves also make sense early in retirement, when sequence-of-returns risk is most acute. As the years pass and your portfolio has demonstrated resilience through at least one or two market cycles, some retirees scale back the short-term buffer in favor of returning more capital to long-term growth vehicles.
Tax Considerations Every HNW Retiree Should Understand
For a retired executive or business owner with significant investment income, the tax treatment of short-term interest income is not a footnote—it directly affects net return and Medicare premiums. This is one area where working with comprehensive wealth management services that include tax planning expertise pays compounding dividends. Getting the best ways to invest money short term right means getting the after-tax math right.
IRMAA and Income Management: A Critical Concern
Medicare’s Income-Related Monthly Adjustment Amount (IRMAA) adds surcharges to your Part B and Part D premiums when your modified adjusted gross income (MAGI) crosses certain thresholds. These thresholds are adjusted annually for inflation, and they carry a two-year lookback: your 2026 Medicare premiums are determined by your 2024 MAGI.
What makes IRMAA particularly dangerous when holding large short-term cash positions: interest income from savings accounts, CDs, Treasury bills, and most bond funds all count toward MAGI. A large CD or savings position can generate enough interest income to push a retiree into—or keep them in—a higher IRMAA bracket. The premium impact can reach several thousand dollars per year for a couple at a higher tier.
The IRS provides detailed guidance on how interest income is reported and taxed at IRS Tax Topic 403. Consult a qualified tax professional to project your specific IRMAA exposure before committing to large taxable interest-bearing positions. Choosing tax-exempt money market funds or municipal bonds—even at a slightly lower gross yield—can produce a meaningfully better after-tax, after-IRMAA outcome.
State Tax Advantages for Florida Retirees
Florida’s absence of a state income tax is one of the most financially significant advantages of retirement in the Sunshine State—and it directly simplifies the short-term investment calculus. Florida retirees receive no additional state-tax benefit from choosing municipal bonds over taxable Treasuries, because both are treated identically at the state level: neither is taxed by Florida.
This means Florida-based high-net-worth retirees should focus their optimization efforts on federal tax efficiency when selecting short-term investment vehicles. At the top federal marginal rate, after-tax yield on savings accounts and CDs is substantially lower than the quoted rate. For investors firmly in the top federal bracket, municipal money market funds may deliver a stronger after-tax result even with a lower nominal yield. The math depends on your specific tax picture—which is precisely why individualized planning matters.
Interest Income and Your Effective Tax Rate
Unlike qualified dividends and long-term capital gains—which receive preferential federal tax rates—interest income from savings accounts, CDs, Treasury bills, and most bond funds is taxed as ordinary income. For a high-income retiree, that’s a significant drag on after-tax returns that doesn’t appear in the headline yield.
A useful exercise before committing to any interest-bearing vehicle: calculate your marginal federal rate and apply it to the gross yield. The result is your after-tax yield. Then calculate the tax-equivalent yield of a comparable municipal alternative. This comparison frequently surprises affluent retirees who have never had someone walk through the math. Running it annually—as your income picture shifts—ensures your short-term investment choices remain optimized.
Comparing the 6 Best Ways to Invest Money Short Term
The table below summarizes the key characteristics of each option. Specific yields vary with market conditions—always verify current rates before investing. Consult a qualified financial professional before making investment decisions.
| Investment Vehicle | Best Time Horizon | Liquidity | Federal Tax Treatment | HNW Suitability |
|---|---|---|---|---|
| High-Yield Savings Account | 0–3 months | High (FDIC-insured) | Fully taxable — ordinary income | Strong for Tier 1 cash reserve |
| Treasury Bills (4–52 weeks) | 1–12 months | High (liquid secondary market) | Exempt from state and local tax | Excellent in taxable accounts |
| Certificates of Deposit / CD Ladder | 3–24 months | Low (early withdrawal penalty) | Fully taxable — ordinary income | Good for predictable cash needs |
| Money Market Mutual Fund | 0–12 months | High (next-day settlement) | Varies by fund type | Excellent; institutional class available |
| Municipal Money Market Fund | 0–12 months | High | Federal tax-exempt | Best for top-bracket investors |
| Short-Term Bond Fund | 12–24 months | Moderate (price can fluctuate) | Fully taxable — ordinary income | Suitable for outer cash ladder tier |
Common Mistakes High-Net-Worth Retirees Make with Short-Term Cash
Identifying the best ways to invest money short term also means recognizing the costly patterns that work against retirees with substantial assets. Three mistakes surface consistently when reviewing how affluent households manage their near-term cash positions.
Mistake #1: Leaving Cash in Low-Yield Checking or Savings Accounts
It is surprisingly common for retirees with $2 million or more in investment assets to hold $200,000 or $300,000 in a primary bank checking account earning effectively nothing. The inertia of convenience is powerful, and the losses are invisible—there’s no statement line showing what was not earned.
The solution is a deliberate, structured review: identify every cash-equivalent holding, determine the purpose and expected time horizon of each position, and match it to the most appropriate short-term investment vehicle. Done properly, this is a one-time exercise that pays persistent dividends.
Mistake #2: Reaching for Yield and Taking on Inappropriate Risk
When interest rates are relatively modest, some retirees extend maturities or accept lower credit quality to improve yield. This approach introduces two meaningful risks in a short-term context. First, longer-duration bonds can suffer material price declines if rates rise, potentially generating negative total returns on funds assumed to be stable. Second, lower-quality credit instruments carry default risk that is fundamentally inconsistent with a capital-preservation objective.
Short-term cash reserves should be boring by design. The goal is protecting principal and earning a fair current return—not maximizing yield. Reaching for extra return in this portion of the portfolio is a category error: it applies long-term investment logic to a short-term liquidity need.
Mistake #3: Ignoring the IRMAA Income Trigger
As discussed, interest income from taxable short-term investments contributes to the MAGI figure that determines Medicare IRMAA surcharges. High-net-worth retirees who place large sums in high-yield taxable instruments without projecting their IRMAA bracket are effectively paying a hidden premium—sometimes thousands of dollars annually—on their Medicare coverage. This is a completely avoidable cost with proper planning.
The solution is to coordinate your short-term investment choices with a full-year income projection, ideally with a fiduciary advisor and a tax professional working together before the tax year begins. For background on Medicare income planning, Kiplinger’s retirement resources provide accessible explanations of how IRMAA brackets work and why income management matters in the years leading up to and through Medicare enrollment.
When to Consider More Sophisticated Short-Term Approaches
For retirees with particularly large liquidity needs—or for those managing cash across multiple account types—there are additional dimensions worth understanding before selecting among the best ways to invest money short term.
Best Ways to Invest Money Short Term Across Different Account Types
Where you hold your short-term cash is as strategically important as what you hold. The right vehicle depends partly on the account type it sits in:
- Taxable brokerage accounts: Prioritize tax-efficient vehicles—T-bills for state tax exemption, municipal money market funds for federal exemption, or tax-managed short-term strategies. Every dollar of taxable interest income here competes against your other income for bracket position and IRMAA exposure.
- Traditional IRA or rollover IRA: Tax efficiency matters less here since all distributions are taxed as ordinary income regardless of how the underlying assets earned returns. Focus on yield and liquidity. The best short-term options in an IRA are generally government or Treasury money market funds.
- Roth IRA: Growth assets—not short-term cash reserves—belong in a Roth to maximize the power of tax-free compounding. Holding significant short-term cash in a Roth is generally suboptimal unless you have a specific reason to access Roth funds in the near term without triggering ordinary income tax.
Coordinating these decisions across your entire account structure is where personalized fiduciary guidance adds the most value. For investors who want to deepen their understanding of short-term fund characteristics and risk metrics, Morningstar provides detailed fund analysis across money market and short-term bond fund categories.
The Role of a Fee-Based Fiduciary in Your Short-Term Cash Strategy
A fee-based fiduciary advisor—one compensated primarily through advisory fees and required to act in your interest when providing investment advice—approaches your short-term cash position not as an isolated question, but as one integrated element of your income, tax, and withdrawal strategy. That coordination is where the real value lies.
Thomas Davies has 30 years in financial services, beginning in 1996. The firm was founded in 2009 and opened its Stuart, Florida office in 2018. We serve high-net-worth individuals, executives, professional athletes, and business owners as a fee-based fiduciary investment adviser registered with the State of Florida. When providing investment advisory services, we act in your interest—and any compensation related to insurance or annuity products is separately and fully disclosed. If you’re ready to connect your short-term cash decisions to a larger coordinated plan, we invite you to schedule a discovery conversation with our team.
Free Download
The Complete Florida Retirement Guide
A comprehensive, plain-English guide to retirement planning in Florida — income strategies, tax considerations, Social Security timing, and healthcare planning for Treasure Coast retirees.
Frequently Asked Questions About Short-Term Investing for Retirees
What are the best ways to invest money short term without losing principal?
The safest options for capital preservation in a 6 to 24 month window include FDIC-insured high-yield savings accounts, Treasury bills backed by the U.S. government, government money market mutual funds, and certificates of deposit from insured institutions. Each carries minimal credit risk, though money market mutual funds are not FDIC-insured. For balances above FDIC insurance limits, T-bills and government money market funds are often the most appropriate solution.
How does IRMAA affect short-term investment decisions for retirees?
IRMAA surcharges on Medicare Part B and Part D are triggered by your modified adjusted gross income, which includes interest income from savings accounts, CDs, and most bond funds. Retirees near an IRMAA tier threshold should factor in the potential premium impact when choosing between taxable and tax-exempt short-term vehicles. A fiduciary advisor and tax professional working together can help you project IRMAA exposure before interest income is earned—when there is still time to adjust the approach.
Are Treasury bills one of the best ways to invest money short term for HNW retirees?
Yes—Treasury bills consistently rank among the strongest short-term options for high-net-worth retirees, particularly in taxable accounts. They are backed by the full faith and credit of the U.S. government, available in maturities from four weeks to 52 weeks, and their interest is exempt from state and local income taxes. They can be purchased through major brokerage platforms or directly through the U.S. Treasury, making access straightforward for most investors.
What is a CD ladder and is it worth building for short-term cash?
A CD ladder divides your short-term cash across multiple certificates of deposit with staggered maturity dates—for example, $100,000 each maturing at 6, 9, 12, and 18 months. As each CD matures, you can access those funds or reinvest at prevailing rates. This structure balances yield optimization with predictable liquidity events and is particularly effective for retirees who have defined, scheduled cash needs over a known window of time.
How much cash should a high-net-worth retiree keep in short-term investments?
A practical guideline for retirees in the distribution phase is to maintain 12 to 24 months of expected net portfolio withdrawals in stable, liquid short-term investments. This buffer insulates your equity and growth portfolio from forced liquidation during a market downturn—directly reducing sequence-of-returns risk. The right amount depends on your income sources, spending variability, upcoming planned expenses, and overall portfolio structure—all factors a fiduciary advisor can help you quantify.
Put Your Short-Term Cash to Work More Intelligently
Identifying the best ways to invest money short term is only part of the equation. The other part—the part that meaningfully affects your after-tax income, your Medicare premiums, and your long-term wealth—is integrating those choices into a coordinated financial plan designed for a retiree with real complexity to manage.
Whether you’re evaluating T-bills versus municipal money market funds, building a CD ladder, or simply trying to stop leaving money in a low-yield checking account, the decisions compound. Getting them right requires understanding how each choice interacts with your tax picture, your IRMAA exposure, and your long-term withdrawal strategy.
Start by understanding where your financial plan stands today. Take our Financial Wellness Quiz—a brief, practical tool that identifies the strongest and weakest areas of your current financial plan, with no obligation and no sales pitch.
Already confident you’re ready for personalized guidance from a fee-based fiduciary? Book a complimentary phone call with the Davies Wealth Management team — a straightforward conversation about your situation and whether our approach is a strong fit for where you are today.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply