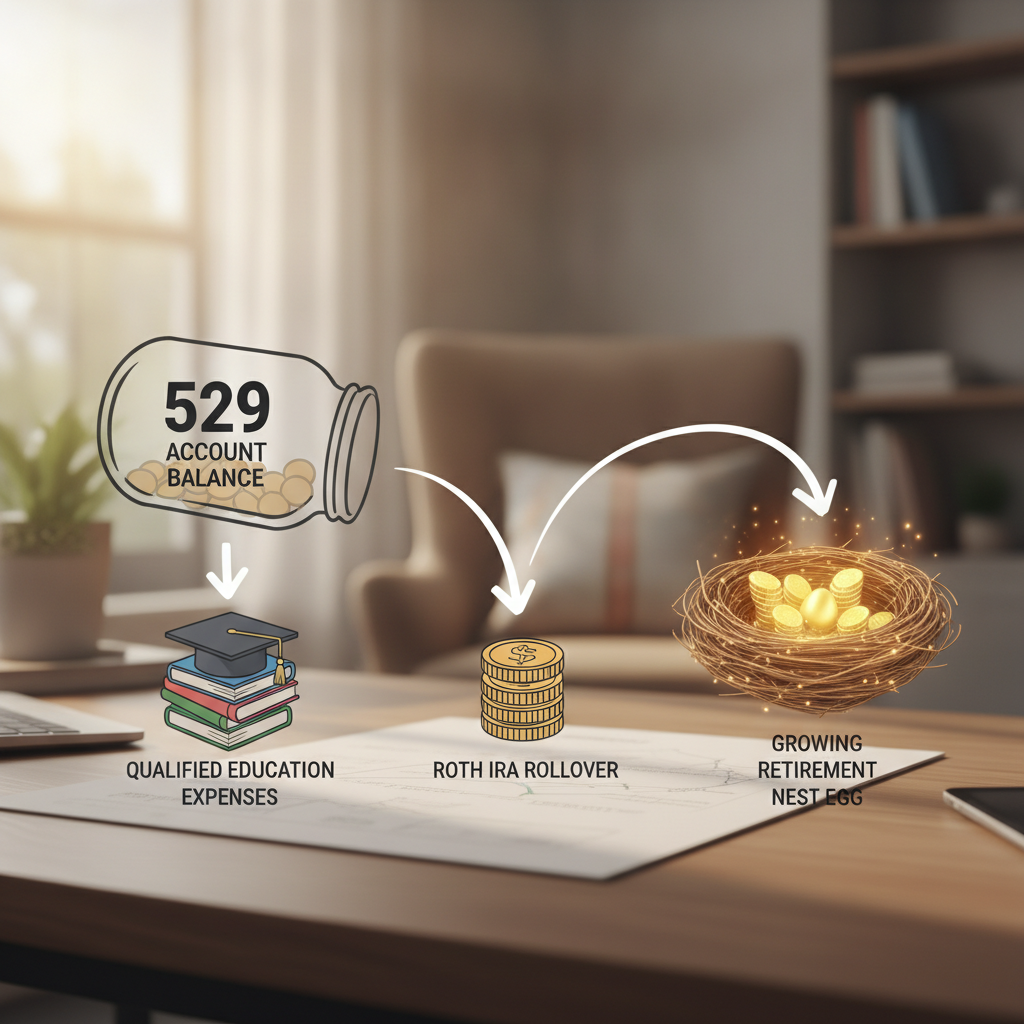
The 529 to Roth IRA rollover is one of the most consequential planning tools introduced for families in the past decade — and one of the least understood. SECURE 2.0, signed into law at the end of 2022 and effective beginning in 2024, created a pathway to roll unused 529 balances directly into a Roth IRA for the account beneficiary. For Stuart families who over-saved for college, funded accounts early, or have a child who earned scholarships, this rule changes the planning calculus entirely.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
This is not a mass-market strategy. The families who benefit most are those who funded 529 accounts aggressively years ago — sometimes starting at birth — and now find themselves holding significant balances their children may not fully use. Before SECURE 2.0, those dollars were essentially trapped: spend them on qualifying education expenses, pay taxes and a 10% penalty to withdraw them, or hold them indefinitely hoping a future grandchild would use them. Now there is a fourth option.
Below, we walk through the seven rules that govern how the 529 to Roth IRA rollover works, who benefits most, and where the planning opportunities — and traps — live.
What SECURE 2.0 Actually Changed for 529 Accounts
The Old Problem With Overfunded 529 Plans
Before SECURE 2.0, the options for surplus 529 funds were limited and often costly. Withdrawing funds for non-qualifying expenses triggered ordinary income tax on the earnings plus a 10% federal penalty. Changing the beneficiary to another family member was possible, but required coordination and sometimes had gift tax implications if generations were skipped.
For high-net-worth families who had funded 529 accounts with $200,000, $300,000, or more per child, an overfunded account wasn’t a minor inconvenience — it represented a meaningful planning failure if those dollars couldn’t be deployed efficiently.
How the 529 to Roth IRA Rollover Works at a High Level
Starting January 1, 2024, Section 126 of SECURE 2.0 allows a direct, tax-free rollover from a 529 account into a Roth IRA owned by the 529 beneficiary. The rollover is treated as a Roth IRA contribution — not a conversion — which means it counts toward the annual Roth IRA contribution limit.
This is a meaningful distinction. The funds move out of the 529, where future growth would be tax-free only if used for qualifying education expenses, and into the Roth IRA, where growth is tax-free for life and subject to no required minimum distributions.
Why This Matters More for High-Net-Worth Families
A family with a $50,000 overfunded 529 account faces a nuisance. A family with a $400,000 overfunded 529 account — common among executives and business owners who maxed contributions from day one — faces a material tax and estate planning decision. The 529 to Roth IRA rollover gives that second family a structured, tax-efficient exit that simply did not exist before 2024.
Contrast this with a mass-market investor who funded a 529 with $25,000 and whose child used every dollar for tuition. That family has no overfunding problem and no need for this strategy. The affluent family that front-loaded contributions, benefited from two decades of compounding, and now has a beneficiary who attended a military academy or earned a full scholarship — that family is exactly who this rule was designed to help.
The 7 Rules Governing the 529 to Roth IRA Rollover
Rule 1: The 529 Account Must Be at Least 15 Years Old
This is the most important timing rule. The 529 account must have been open for a minimum of 15 years before any rollover can occur. The clock starts from the original account opening date — not from when contributions were made or when the beneficiary was designated.
This rule rewards families who opened accounts early. A parent who opened a 529 at a child’s birth in 2010 can begin rolling funds in 2025. A parent who opened the account in 2018 must wait until 2033. Planning ahead matters.
Important nuance: Changing the beneficiary may reset the 15-year clock, though IRS guidance on this point continues to evolve. Consult a qualified tax professional before making any beneficiary change on an account you intend to use for a rollover.
Rule 2: There Is a $35,000 Lifetime Rollover Cap Per Beneficiary
The 529 to Roth IRA rollover is capped at $35,000 per beneficiary over their lifetime. This is not an annual limit — it is a cumulative lifetime maximum. Once a beneficiary has received $35,000 in rollovers, no further 529-to-Roth rollovers are permitted for that individual.
For families with $200,000 or more in an overfunded 529, this cap means the rollover addresses only a portion of the surplus. Other strategies — changing beneficiaries, making qualified withdrawals, or holding for future generations — will still be needed for the remaining balance.
Rule 3: Annual Rollovers Are Limited to the Roth IRA Contribution Limit
Each year, the amount rolled from a 529 to a Roth IRA cannot exceed the annual Roth IRA contribution limit for that year. In 2026, the standard contribution limit is $7,000 per year, with an additional $1,000 catch-up for those 50 and older.
This means reaching the $35,000 lifetime cap takes a minimum of five years under current limits. Families should plan for a multi-year rollover strategy rather than a single lump-sum transfer.
Rule 4: The Roth IRA Must Be in the Beneficiary’s Name
The rollover goes into a Roth IRA owned by the 529 plan’s beneficiary — not the account owner (typically the parent). This is a critical structural point. The parent who owns the 529 cannot roll the funds into their own Roth IRA. The beneficiary — the child — receives the Roth IRA benefit.
For high-net-worth families thinking about multi-generational wealth transfer, this is a meaningful feature. Each year of rollover seeds a growing, tax-free account in the child’s name. Over decades, even $35,000 compounded inside a Roth IRA can represent a substantial inheritance-free, tax-free asset.
Rule 5: The Beneficiary Must Have Earned Income (Up to the Rollover Amount)
Like a regular Roth IRA contribution, the beneficiary must have earned income in the year of the rollover that is at least equal to the amount being rolled over. A child who earned $5,000 working part-time can receive up to $5,000 in a rollover that year, even if the annual limit is $7,000.
This rule can slow the process for young beneficiaries who are full-time students without meaningful income. Families should coordinate the rollover timing with the beneficiary’s employment history. A beneficiary who begins working after graduation and earns well above the contribution limit can roll the full annual amount each year until the $35,000 cap is reached.
Rule 6: Contributions Made in the Prior 5 Years Are Ineligible
Contributions made to the 529 account within the five years immediately preceding the rollover are not eligible to be rolled over. This prevents a strategy of making a large lump-sum contribution to a seasoned 529 account and immediately converting those new dollars to a Roth IRA.
The practical effect: only “seasoned” contributions — those made more than five years before the rollover — are eligible. For families with older accounts, most of the balance will clear this threshold. For families who recently added funds, patience is required.
Rule 7: Income Limits for Roth IRA Eligibility Do Not Apply
This is one of the most underappreciated aspects of the 529 to Roth IRA rollover. Normally, high earners are phased out of direct Roth IRA contributions entirely. In 2026, the Roth IRA phase-out for single filers begins at modified AGI well above six figures, and for married filers even higher. Above those thresholds, direct Roth contributions are reduced or eliminated.
The 529-to-Roth rollover bypasses these income limits entirely. A beneficiary who earns $500,000 per year and would otherwise be ineligible to contribute to a Roth IRA can still receive a 529 rollover — as long as they have earned income equal to the rollover amount. This makes the strategy particularly powerful for beneficiaries who go on to become high-earning professionals.
Comparing Your Options for an Overfunded 529 Account
Understanding the 529 to Roth IRA rollover is easier in context. Here is how it compares to the other available options for a family with surplus funds in a 529 account.
| Option | Tax on Earnings | Penalty | Best For |
|---|---|---|---|
| 529 to Roth IRA Rollover | None (if rules met) | None | Seasoned accounts, 15+ year holding period, beneficiary with earned income |
| Change Beneficiary to Sibling | None if used for education | None | Families with younger children who will attend college |
| Change Beneficiary to Grandchild | None if used for education | Potential generation-skipping tax implications | Long-horizon multi-generational education funding |
| Non-Qualified Withdrawal | Ordinary income on earnings | 10% federal penalty on earnings | Last resort; rarely optimal |
| Scholarship Exception Withdrawal | Ordinary income on earnings | No penalty (penalty waived up to scholarship amount) | Beneficiary received significant scholarship awards |
For most high-net-worth families, the 529 to Roth IRA rollover is the most tax-efficient option available for genuine surplus — dollars that genuinely will not be used for qualifying education expenses. The $35,000 cap means it is rarely a complete solution for large overfunded accounts, but it is almost always part of the right answer.
Strategic Planning Opportunities for HNW Families
Layering the Rollover With Other Roth Strategies
The annual rollover does not displace other Roth planning. If a beneficiary qualifies for a direct Roth IRA contribution in the same year, they can make both the 529 rollover and a standard Roth contribution — as long as the combined total does not exceed the annual contribution limit. This creates a narrow window for maximizing Roth contributions in years where the beneficiary has significant earned income but remains below the income phase-out threshold.
For high-earning beneficiaries who are already phased out of direct contributions, the rollover stands alone as a way to get funds into a Roth IRA — a benefit unavailable through any other mechanism at their income level.
Using the Rollover as a Multi-Generational Wealth Transfer Tool
When a beneficiary receives a 529 to Roth IRA rollover each year over five or more years, the cumulative Roth IRA balance — combined with decades of tax-free compounding — can represent a significant, inheritance-efficient asset. Roth IRAs are not subject to required minimum distributions during the owner’s lifetime, meaning the account can compound indefinitely if the beneficiary does not need the funds.
Paired with a well-structured estate plan, this can become a meaningful component of a family’s multi-generational wealth transfer strategy. Working with a firm that provides comprehensive wealth management services ensures these pieces are coordinated rather than handled in isolation.
529 to Roth IRA Rollover and the State Tax Question
Federal rules are clear, but state tax treatment of 529-to-Roth rollovers varies. Some states that previously allowed a deduction for 529 contributions may attempt to recapture that deduction if funds are not used for qualifying education expenses — including rollovers to a Roth IRA. Florida has no state income tax, so Stuart-area families face no state-level recapture risk. But families with 529 accounts held in other states or who have recently relocated should verify their state’s treatment before executing a rollover. Consult a qualified tax professional for your specific situation.
Timing the Rollover Around the Beneficiary’s Tax Situation
Because the rollover counts as a Roth IRA contribution — not a conversion — it does not create taxable income. There is no IRMAA exposure, no bracket-pushing, and no impact on the beneficiary’s Medicare premiums in future years. This makes timing relatively flexible compared to a Roth conversion strategy, where bracket management is critical.
That said, the earned income requirement means coordination with the beneficiary’s employment calendar matters. Executing rollovers in years of strong earned income ensures eligibility and maximizes the annual rollover amount.
Common Mistakes to Avoid With the 529 to Roth IRA Rollover
Overlooking the 15-Year Account Age Requirement
Families sometimes assume that because their child is 18 or 22, the 529 account is old enough. The account age — not the beneficiary’s age — controls eligibility. A 529 account opened when the child was 10 years old is only 8 years old at the child’s 18th birthday. Verify account opening dates before planning a rollover timeline.
Confusing the $35,000 Cap With an Annual Limit
The $35,000 cap is a lifetime maximum per beneficiary, not an annual allowance. Families who misread this may believe they can roll $35,000 per year indefinitely. In reality, once the cumulative rollovers reach $35,000, no further 529-to-Roth rollovers are permitted for that beneficiary — ever.
Ignoring the 5-Year Contribution Seasoning Rule
Making a large contribution to an overfunded 529 account and attempting to immediately roll it to a Roth IRA will not work. Contributions made within the prior five years are ineligible. Families who add funds to a 529 with rollover intent must plan for a five-year waiting period before those specific dollars can move.
Failing to Coordinate With the Beneficiary
The Roth IRA belongs to the beneficiary, not the parent. The parent owns the 529, but the beneficiary must have an open Roth IRA account, must have earned income in the rollover year, and should understand the contribution being credited to their account. This requires active communication and coordination — something a fiduciary wealth advisor can help facilitate across the family unit.
Free Download
The Complete Florida Retirement Guide
A comprehensive, plain-English guide to retirement planning in Florida — income strategies, tax considerations, Social Security timing, and healthcare planning for Treasure Coast retirees.
Frequently Asked Questions About the 529 to Roth IRA Rollover
Can a parent roll their own 529 account into their own Roth IRA?
No. The 529 to Roth IRA rollover must go into a Roth IRA belonging to the 529 plan’s designated beneficiary, not the account owner. If a parent is both the owner and the beneficiary of the 529, a rollover into the parent’s Roth IRA may be possible, but this is a relatively uncommon account structure. Consult a qualified tax professional to verify your specific account setup.
Does the 529 to Roth IRA rollover count against the annual Roth IRA contribution limit?
Yes. The rollover is treated as a Roth IRA contribution and is subject to the same annual limit — $7,000 in 2026, plus $1,000 catch-up for those 50 and older. The rollover and any direct contributions made in the same year cannot exceed this combined limit.
What happens if the beneficiary does not have a Roth IRA yet?
The beneficiary must open a Roth IRA before the rollover can be executed. There is no special rule that creates the account automatically. This is straightforward — most major custodians allow beneficiaries to open a Roth IRA online — but it is a step that must be completed before the transfer is initiated.
Can the 529 to Roth IRA rollover be reversed if the beneficiary later needs the funds for college?
No. Once funds are rolled from the 529 into the Roth IRA, they are governed entirely by Roth IRA rules. They cannot be moved back into a 529 account. Before executing a rollover, confirm with reasonable certainty that the funds are genuinely surplus to the beneficiary’s education needs.
How does the 529 to Roth IRA rollover interact with estate planning for high-net-worth families?
The rollover moves assets out of a 529 plan (which is included in the owner’s estate) and into a Roth IRA owned by the beneficiary. This effectively removes the funds from the parent’s estate while seeding the beneficiary’s tax-free retirement account. For families focused on efficient wealth transfer, this is a meaningful secondary benefit beyond the tax-free growth itself.
How Davies Wealth Management Approaches 529 Planning
In working with clients across Stuart and the broader Treasure Coast, many of the families we see have been diligent savers — sometimes too diligent. A 529 account opened at a child’s birth with consistent maximum contributions and two decades of market growth can easily outpace even a private university education.
The 529 to Roth IRA rollover is rarely a standalone decision. It intersects with the beneficiary’s income, the parent’s estate plan, existing Roth conversion strategies, IRMAA planning, and the family’s broader wealth transfer goals. Treating it as an isolated account transaction misses the larger opportunity.
As a fee-based fiduciary when providing investment-advisory services, Davies Wealth Management reviews these decisions within the full context of a family’s financial picture — not as a product sale, but as part of an integrated plan. Insurance commissions, where applicable, are separately disclosed.
If you are managing a 529 account with more than $100,000 in surplus, or if your child recently graduated, earned significant scholarships, or changed educational plans, now is the right time to review your options. You can learn more about our approach through our comprehensive wealth management services page, or schedule a discovery conversation with our team.
For additional reading on SECURE 2.0 provisions, the IRS SECURE 2.0 Questions and Answers page provides official guidance. Kiplinger’s coverage of 529-to-Roth rollovers offers a useful consumer-level overview. For detailed contribution rules, Fidelity’s 529-to-Roth IRA rollover guide and NerdWallet’s detailed breakdown are both helpful supplementary resources.
The bottom line: the 529 to Roth IRA rollover is a genuinely valuable planning tool — one that rewards families who planned early and now need an intelligent way to deploy surplus college savings. The rules are specific, the limits are real, and the coordination required across tax, estate, and investment planning is exactly where a fiduciary advisor earns their value. Consult a qualified financial and tax professional before executing any rollover strategy.
Take the Next Step
Wondering whether your family’s 529 situation warrants a rollover strategy? Start by understanding your complete financial picture.
→ Take our Financial Wellness Quiz to identify planning gaps and opportunities across your full wealth picture — including education accounts, retirement strategy, and tax efficiency.
→ Ready for personalized guidance from a fee-based fiduciary? Book a complimentary phone call with the Davies Wealth Management team to discuss your specific situation.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply