
The step-up in basis is one of the most powerful tax provisions in the entire U.S. tax code—and one that high-net-worth families frequently underutilize simply because they don’t fully understand how it works. When you inherit appreciated assets, the tax rules treat those assets as if you purchased them at their current fair market value, potentially eliminating decades of embedded capital gains overnight.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
For families with significant investment portfolios, real estate holdings, or concentrated stock positions, understanding this rule is not optional. It directly shapes how you structure your estate, which assets you give away during life versus at death, and how your heirs ultimately preserve what you’ve built.
This guide explains the step-up in basis rules clearly—including what qualifies, what doesn’t, and the planning strategies that matter most when you have $1 million or more in appreciated assets.
What Is Step-Up in Basis and Why Does It Matter for HNW Families?
The Core Definition of Step-Up in Basis
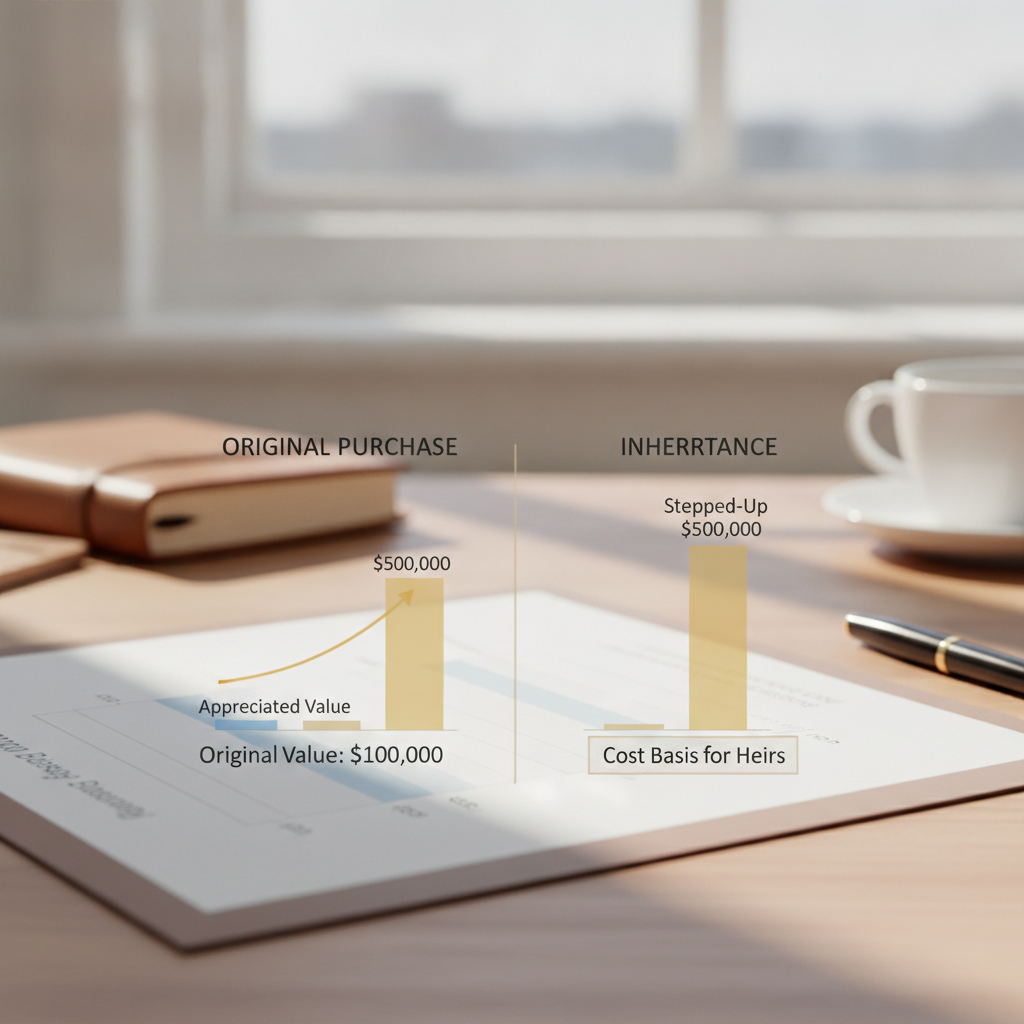
Basis is simply your starting point for calculating capital gains. If you bought stock for $50,000 and later sell it for $200,000, your taxable gain is $150,000—your proceeds minus your basis. That gain gets taxed at capital gains rates, which at higher income levels can reach 23.8% federally when the net investment income tax (NIIT) is included.
The step-up in basis rule, governed primarily by IRS Publication 559 and codified under IRC Section 1014, changes the calculation entirely for inherited assets. When you inherit property, your basis is “stepped up” to the asset’s fair market value on the date of the decedent’s death—not what the original owner paid for it.
That means the $150,000 gain in the example above? It simply disappears upon inheritance. The heir who sells immediately after inheriting owes little to nothing in capital gains tax.
How Significant Is the Tax Impact?
For mass-market investors with modest portfolios, this rule is a nice benefit. For high-net-worth families with decades of portfolio appreciation, it can represent a substantial elimination of potential capital gains liability.
Consider a family with a $5 million stock portfolio originally purchased at an average cost of $1 million. The embedded gain is $4 million. At a 23.8% combined federal rate, that’s nearly $1 million in deferred taxes sitting inside that portfolio. The step-up in basis rule makes that entire liability vanish at death—provided the assets pass through the estate rather than by gift during the owner’s lifetime.
This is precisely why the step-up in basis is worth understanding at a sophisticated level—not just the basics.
How the Step-Up in Basis Actually Works: The Mechanics
Assets That Qualify for a Step-Up in Basis
Not all inherited assets receive a step-up. The general rule applies to assets included in the decedent’s taxable estate for federal estate tax purposes. This typically includes:
- Individually owned stocks, bonds, and mutual funds
- Real estate (primary homes, investment properties, vacation homes)
- Concentrated stock positions from employer equity compensation
- Collectibles and tangible personal property of significant value
- Brokerage accounts held in the decedent’s name
Closely held business interests (partnerships, LLCs, S-corporations, depending on structure)
The key principle: if the asset’s value is included in the gross estate, the heir generally receives a stepped-up basis. Consult a qualified tax professional for your specific situation, particularly when business interests or complex ownership structures are involved.
Assets That Do NOT Receive a Step-Up in Basis
Several important asset categories are excluded from the step-up rule, and high-net-worth families are often surprised by this list:
- Traditional IRAs and 401(k)s — these pass with their full embedded ordinary income tax liability intact. The heir pays income tax on withdrawals, not capital gains rates.
- Roth IRAs — no step-up, but qualified distributions remain tax-free.
- Annuities — gains are subject to ordinary income tax upon withdrawal.
- Assets transferred by gift during life — gifts carry over the original donor’s basis (called “carryover basis”), not a step-up.
- Certain grantor trust assets — depending on structure and applicable law, some trust-held assets may not receive the step-up.
This distinction matters enormously for asset location and estate planning decisions. Which accounts you draw from during life—and which you leave to heirs—has real tax implications.
Community Property States and the Double Step-Up
Married couples in community property states benefit from an additional advantage: the double step-up in basis. Under this rule, when one spouse dies, both halves of community property receive a stepped-up basis—not just the deceased spouse’s half.
Florida is not a community property state, but it does allow married couples to hold property as tenants by the entirety, and some states like California, Arizona, and Nevada offer community property treatment. Clients who have moved from community property states or who own property in multiple states should work with advisors who understand how these rules interact with their overall estate plan.
Step-Up in Basis Planning Strategies for High-Net-Worth Families
Strategy 1: Hold Highly Appreciated Assets Until Death
The most straightforward application of the step-up in basis rule is simply not selling appreciated assets during life if you don’t need to. Holding concentrated positions, appreciated real estate, or low-basis stock in taxable accounts until death transfers them with a stepped-up basis—permanently eliminating the deferred gain.
This runs counter to the instinct to diversify immediately, which is why the analysis matters. For a client in their 70s with a $3 million concentrated stock position and a basis of $200,000, the tax cost of selling during life is significant. Structured properly through the estate, the heirs inherit diversified or liquidated proceeds without that tax burden.
This is not about avoiding all taxes forever—it’s about timing and structure. Work with a qualified financial and tax professional to analyze the tradeoffs for your specific portfolio.
Strategy 2: Avoid Gifting Low-Basis Assets During Life
One of the most common—and costly—mistakes high-net-worth families make is gifting appreciated assets during their lifetime. When you gift stock or real estate to a child or grandchild, they receive your original basis (carryover basis), not a step-up.
Compare two approaches for a parent wanting to transfer $500,000 of appreciated stock with a $50,000 original basis:
| Transfer Method | Recipient’s Basis | Taxable Gain on Sale | Potential Tax Cost |
|---|---|---|---|
| Lifetime gift | $50,000 (carryover) | $450,000 | Up to 23.8% federally on gain |
| Inherited at death | $500,000 (step-up) | $0 (if sold promptly) | Effectively zero capital gains |
| Gift of cash (from sale) | N/A | Paid by donor at sale | Donor pays tax; recipient gets cash |
| Charitable gift of appreciated stock | N/A (charity exempt) | None (no gain recognized) | Donor gets deduction; no tax on gain |
This table illustrates why gifting cash or higher-basis assets during life—while preserving low-basis appreciated assets for the estate—is often the more tax-efficient strategy for HNW families.
Strategy 3: Charitable Giving with Low-Basis Assets
If you want to be charitable and you hold appreciated assets, donating them directly to a qualified charity—or to a donor-advised fund (DAF), charitable remainder trust (CRT), or other vehicle—can be highly efficient. You receive a fair market value deduction, and neither you nor the charity pays capital gains tax on the appreciation.
This strategy pairs well with preserving low-basis stock for heirs. Donate appreciated assets with the lowest relative value to you (assets you’d sell anyway), and retain others for the step-up in basis benefit at death. A charitable remainder trust can also provide income during your lifetime while removing the asset from your estate. Consult a qualified estate planning attorney and tax advisor before implementing any charitable trust structure.
Strategy 4: Qualified Opportunity Zone Investments
High-net-worth investors with large capital gains may also consider Qualified Opportunity Zone (QOZ) investments as part of a broader strategy. While not directly a step-up mechanism, these investments allow deferral and potential reduction of capital gains when proceeds are reinvested in designated opportunity zones. The rules are complex and time-sensitive. Consult a qualified tax professional to evaluate whether QOZ investments fit your situation.
Strategy 5: Trust Structures and Step-Up Considerations
Not all trusts preserve the step-up in basis benefit. This is an area where HNW families need careful guidance, because the wrong trust structure can inadvertently lock in carryover basis.
Key considerations:
- Revocable living trusts — assets in a revocable trust are still part of the taxable estate at death and do receive a step-up in basis. This is a common misconception.
- Irrevocable grantor trusts — assets transferred out of the estate to irrevocable trusts typically use the gift rules (carryover basis), not the step-up. However, certain grantor trust structures may allow assets to be “swapped” back into the estate to capture the step-up. This is a specialized strategy that requires coordination between your estate planning attorney and tax advisor.
- QTIP trusts and marital trusts — assets in a qualified terminable interest property (QTIP) trust generally receive a step-up at the surviving spouse’s death, since they’re included in that spouse’s taxable estate.
- Irrevocable life insurance trusts (ILITs) — life insurance proceeds inside an ILIT are excluded from the estate and not subject to capital gains, so the step-up issue doesn’t apply in the same way.
The critical takeaway: before transferring appreciated assets into any irrevocable structure, model the step-up tradeoff carefully with your planning team.
Step-Up in Basis in Today’s Estate Planning Environment
The Current Federal Estate Tax Landscape
Thanks to the One Big Beautiful Bill Act signed into law in July 2025, the federal estate and gift tax exemption is now permanently set at $15 million per individual and $30 million per married couple, indexed for inflation going forward. This permanence removes the planning uncertainty that dominated conversations in prior years.
What does this mean for the step-up in basis? For the vast majority of HNW families, federal estate taxes are no longer the primary concern—the focus shifts to income tax planning and capital gains optimization within the estate. The step-up in basis becomes even more strategically important because more assets will pass to heirs without triggering estate tax, making the question of how those assets are taxed after transfer central to the planning conversation.
State-Level Estate Taxes Still Matter
Florida has no state estate tax, which is one reason it remains a popular destination for retirees and executives relocating from states like Massachusetts, Oregon, or Washington—all of which impose their own estate taxes with exemptions far below the federal level.
If you own real estate or have domicile ties to states with estate taxes, the step-up in basis and state-level estate tax planning interact in important ways. A Florida-based fiduciary advisor can help model the full picture, particularly if you have multi-state assets or recently relocated. For more information on relocating to Florida and its tax advantages, see our Florida Relocation Guide.
How the Step-Up in Basis Differs from Strategies for Mass-Market Investors
Advisors serving the general public often emphasize diversification above all else—sell concentrated positions, spread the risk. That advice is not wrong, but it’s incomplete for HNW families with significant embedded gains.
At Davies Wealth Management, our comprehensive wealth management services integrate income tax planning, estate planning, and investment management so that decisions about when and how to sell appreciated assets reflect the full picture—not just the investment merit in isolation.
A mass-market investor with $200,000 in a 401(k) doesn’t need to worry about step-up basis planning. A client with $3 million in a taxable brokerage account, another $2 million in real estate, and a significant IRA balance needs a coordinated plan that considers which assets to hold, which to give, and which to leave for heirs.
Practical Steps for HNW Families Right Now
Step 1: Know Your Basis
Many investors have no idea what their current cost basis is—especially for assets held for decades, inherited previously, or transferred in a business transaction. Knowing your basis is the foundation of all step-up planning.
Start by reviewing your brokerage statements and asking your custodian for a cost basis report. For real estate, gather your original purchase documents, records of capital improvements, and any depreciation schedules. For inherited assets you already hold, verify whether the basis was properly stepped up at the time you inherited them.
Step 2: Categorize Assets by Tax Character
Not all assets are equally tax-efficient for different purposes. A useful framework:
- High-appreciation, low-basis taxable assets → strong candidates to hold for the step-up at death or donate to charity
- IRA and retirement accounts → no step-up available; consider Roth conversions to manage future income tax burden
- High-basis or recently purchased taxable assets → better candidates for lifetime gifts to heirs
- Life insurance cash value → different rules apply; evaluate with your advisor
Step 3: Coordinate with Your Estate Plan
Your will, revocable trust, and beneficiary designations all affect which assets pass through the estate (and get the step-up) versus which pass by other means. This coordination should be reviewed every few years and after any major life event—marriage, divorce, birth of a grandchild, significant change in asset values.
If you haven’t reviewed your estate plan since the OBBBA permanently raised the federal exemption, now is a good time to revisit the structure with your estate planning attorney. The goals haven’t changed—efficient transfer of wealth to your heirs and chosen causes—but the tools and priorities may have shifted.
Step 4: Work With Advisors Who Coordinate Across Disciplines
The step-up in basis planning doesn’t live in a silo. It requires coordination among your financial advisor, CPA, and estate planning attorney. At firms managing HNW relationships, this coordination is standard—which is a meaningful difference from working with a broker or national wirehouse where investment management and tax planning rarely speak to each other.
If you’re working with advisors who have never discussed your cost basis, your estate plan, or how your charitable giving interacts with your inheritance strategy, that’s a signal worth noting. Families with $500,000 or more in investable assets generally need a more coordinated approach. To schedule a discovery conversation, we’re happy to explore whether a more integrated planning relationship makes sense for your situation.
Frequently Asked Questions About Step-Up in Basis
What is the step-up in basis rule for inherited assets?
The step-up in basis rule (IRC Section 1014) resets an inherited asset’s cost basis to its fair market value on the date of the original owner’s death. This eliminates any capital gains that accumulated during the original owner’s lifetime, meaning heirs who sell immediately typically owe little or no capital gains tax on that appreciation.
Do assets in a revocable living trust receive a step-up in basis?
Yes. Assets held in a revocable living trust are still included in the decedent’s taxable estate and receive a step-up in basis at death, the same as assets held in the owner’s individual name. The trust does not change the step-up treatment; it simply governs how the assets are distributed to heirs without going through probate.
Does a step-up in basis apply to inherited IRA accounts?
No. IRAs and other tax-deferred retirement accounts do not receive a step-up in basis. When heirs inherit a traditional IRA, they pay ordinary income tax on withdrawals—not capital gains rates. This is why IRAs are often the last accounts to draw from during life and why Roth conversion planning can be so valuable for reducing the income tax burden passed to heirs.
What happens to step-up in basis for jointly held assets?
For assets held as joint tenants with right of survivorship (JTWROS) between non-spouses, only the deceased owner’s share of the asset typically receives a step-up in basis. For married couples in common law states like Florida, spousal jointly held property generally results in a step-up for one-half of the asset at the first spouse’s death. Community property rules differ significantly and can allow both halves to receive a step-up.
Can you lose the step-up in basis through certain planning strategies?
Yes. Transferring appreciated assets to an irrevocable trust during your lifetime removes them from your taxable estate, which eliminates the step-up in basis benefit. Similarly, gifting appreciated assets directly to heirs during life gives them your original carryover basis, not a stepped-up one. This tradeoff—estate tax removal versus loss of step-up—is a central consideration in advanced estate planning, particularly now that the federal exemption is permanently elevated.
Bringing It All Together: The Step-Up in Basis as a Wealth Preservation Tool
The step-up in basis is not a loophole or an obscure tax trick. It is a foundational feature of the U.S. tax code that rewards long-term wealth accumulation and thoughtful estate planning. For high-net-worth families who have spent decades building portfolios, businesses, and real estate holdings, this rule represents one of the most significant tax planning opportunities available.
The families who benefit most from it are not those who stumble into it—they’re the ones whose advisors actively planned for it. That means knowing which assets to hold, which to give, how trusts interact with the step-up, and how retirement accounts fit into the broader picture.
At Davies Wealth Management, Thomas Davies brings 30 years of financial services experience beginning in 1996, and the firm has been serving clients from its Stuart, Florida office since 2018. As a fee-based fiduciary when providing investment-advisory services, Davies Wealth Management works with clients who have at least $500,000 in investable assets and who value integrated, tax-aware planning—not just portfolio management in isolation.
If you have appreciated assets and you haven’t had a step-up in basis conversation with your advisory team, it’s worth having one. The strategies are well-established. The decisions are time-sensitive in the sense that some planning only works before—not after—a transfer occurs. And the differences in outcome can be meaningful for the generation that inherits what you’ve built.
For more on how IRS rules govern inherited property, see IRS Topic 703: Basis of Assets. Additional background on estate planning and wealth transfer is available through Fidelity’s Estate Planning Overview, Kiplinger’s guide to inheritance taxes, and the NerdWallet capital gains tax guide.
Ready to Review Your Step-Up in Basis Strategy?
Understanding the step-up in basis is the first step. Applying it intelligently to your specific portfolio, estate plan, and family situation is where the real work—and the real value—lies.
Take our Financial Wellness Quiz to quickly identify where your wealth plan may have gaps—including in tax-efficient wealth transfer planning.
👉 Take the Financial Wellness Quiz
Or if you’re ready to have a direct conversation about your estate plan, inherited assets, or low-basis portfolio positions, we’re here to help.
👉 Book a complimentary phone call with Davies Wealth Management
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply