The 403(b) annuity has long been the workhorse of retirement savings for teachers, professors, hospital workers, and nonprofit professionals — yet most participants barely scratch the surface of what this vehicle can do. If you have spent decades contributing to a 403(b) and are approaching retirement with a substantial balance, the real question is no longer how to accumulate more. The question is how to turn what you have built into reliable, tax-efficient income that lasts as long as you do.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
This guide is written for educators, healthcare professionals, and nonprofit executives who have accumulated $500,000 or more in a 403(b) plan — and who want a clear, sophisticated framework for converting that wealth into a retirement paycheck. We will cover the mechanics, the strategies, the trade-offs, and the questions you should be asking before you make any irreversible decisions.
What Is a 403(b) Annuity and Who Qualifies?
The Basics of a 403(b) Plan
A 403(b) plan is a tax-advantaged retirement savings vehicle available to employees of public schools, universities, hospitals, and 501(c)(3) nonprofit organizations. It operates similarly to a 401(k) but with a few important structural differences — most notably, the traditional use of annuity contracts as the underlying investment vehicle, which is where the term 403(b) annuity originates.
Contributions are made on a pre-tax basis (or after-tax basis in a Roth 403(b)), grow tax-deferred, and are subject to ordinary income tax upon withdrawal. The IRS permits high contribution limits, and eligible employees with 15 or more years of service at certain organizations may qualify for an additional catch-up provision beyond the standard catch-up limit available to savers over age 50. Consult a qualified tax professional to confirm eligibility for these provisions in your specific situation.
Annuity Contracts Within a 403(b)
Historically, 403(b) plans were required to hold annuity contracts — insurance products that can provide a stream of income payments. Today, many 403(b) plans also offer custodial accounts holding mutual funds, but the annuity structure remains common, particularly in K-12 school districts and healthcare systems.
Understanding what type of 403(b) annuity you own matters enormously at retirement. The two primary categories are:
- Fixed annuities: Provide a guaranteed interest rate and principal protection. Suitable for conservative savers who prioritize stability.
- Variable annuities: Invest in sub-accounts tied to market performance. Returns fluctuate, but many include optional riders that provide a guaranteed income floor.
A third category — the fixed indexed annuity — links potential growth to a market index while protecting against downside loss. Each structure has meaningfully different cost profiles, payout options, and tax implications.
Why High-Balance 403(b) Holders Face Different Decisions Than Average Savers
The Complexity Gap at Higher Account Balances
Most retirement planning content is built for the median worker with a few hundred thousand dollars accumulated. If you are approaching retirement with $750,000, $1.5 million, or more in a 403(b) annuity, the stakes and the strategy shift considerably.
At this level, decisions about when and how to take distributions can affect your Medicare premiums through IRMAA (Income-Related Monthly Adjustment Amounts), your Social Security taxation, your estate, and potentially your heirs’ inherited income tax burden. These are not concerns the average school district HR department is equipped to address.
How HNW Educators Differ From Mass-Market Advice Targets
Consider how standard 403(b) guidance compares to what a high-balance participant actually needs:
| Topic | Standard 403(b) Guidance | HNW 403(b) Annuity Strategy |
|---|---|---|
| Distribution timing | Take income when you retire | Model income against IRMAA thresholds and bracket management |
| Roth conversion | Rarely discussed | Multi-year Roth conversion ladder to reduce RMD exposure |
| Beneficiary planning | Name a spouse or child | Coordinate with trust structure and 10-year inherited IRA rules |
| Annuity payout election | Single or joint life annuity | Partial annuitization combined with liquid reserves and Roth assets |
| Required Minimum Distributions | Take the minimum | Proactively reduce future RMDs through Roth conversions and charitable giving |
7 Proven Strategies to Convert Your 403(b) Annuity Into Guaranteed Income
Strategy 1: Understand Your Annuitization Options Before You Elect
Many 403(b) annuity contracts include a built-in annuitization option — the ability to convert your accumulated balance into a series of guaranteed monthly payments. This is a permanent, typically irrevocable election, which makes understanding your options before you sign critically important.
Common payout structures include:
- Life-only annuity: Highest monthly payment; payments cease at death with no residual value to heirs.
- Joint and survivor annuity: Continues at a reduced percentage (typically 50–100%) for a surviving spouse. Lower initial payout than life-only.
- Period certain annuity: Guarantees payments for a fixed period (often 10 or 20 years), regardless of longevity.
- Life with period certain: A hybrid — income for life, with a minimum guarantee period protecting heirs if you die early.
For married couples with significant assets, a joint and survivor annuity combined with a well-funded liquid portfolio often creates more flexibility than a life-only election with higher monthly payments. Consult a qualified financial professional to model the trade-offs for your specific situation.
Strategy 2: Use Partial Annuitization to Preserve Flexibility
One of the most underutilized features in a 403(b) annuity context is partial annuitization — converting only a portion of your accumulated balance into guaranteed income while keeping the remainder invested or liquid.
This approach can serve as a “retirement income floor” — a guaranteed base of income to cover fixed expenses — while leaving growth assets available for inflation protection, healthcare needs, or legacy goals. The IRS clarified rules around partial annuitization in 2014, making it more accessible for many contract holders. Always verify whether your specific contract permits partial annuitization, as terms vary by insurer.
Strategy 3: Execute a Disciplined Roth Conversion Ladder Before RMDs Begin
If your 403(b) annuity balance is large, Required Minimum Distributions — which begin at age 73 under current law — can generate substantial taxable income in years when you may also be collecting Social Security and pension income. That combination can push you into higher brackets and trigger IRMAA surcharges on Medicare Part B and Part D premiums.
A Roth conversion ladder involves moving a calculated portion of your pre-tax 403(b) balance into a Roth IRA each year during the gap between retirement and RMD onset. The converted amounts are taxable in the year of conversion, but future growth and qualified withdrawals are tax-free, and Roth accounts are not subject to RMDs during the owner’s lifetime.
For a high-balance 403(b) holder, coordinating conversions to fill — but not exceed — a specific tax bracket each year requires careful planning. Consult a qualified tax professional to determine the optimal annual conversion amount for your situation.
Strategy 4: Coordinate Your 403(b) Annuity Distributions With Social Security Timing
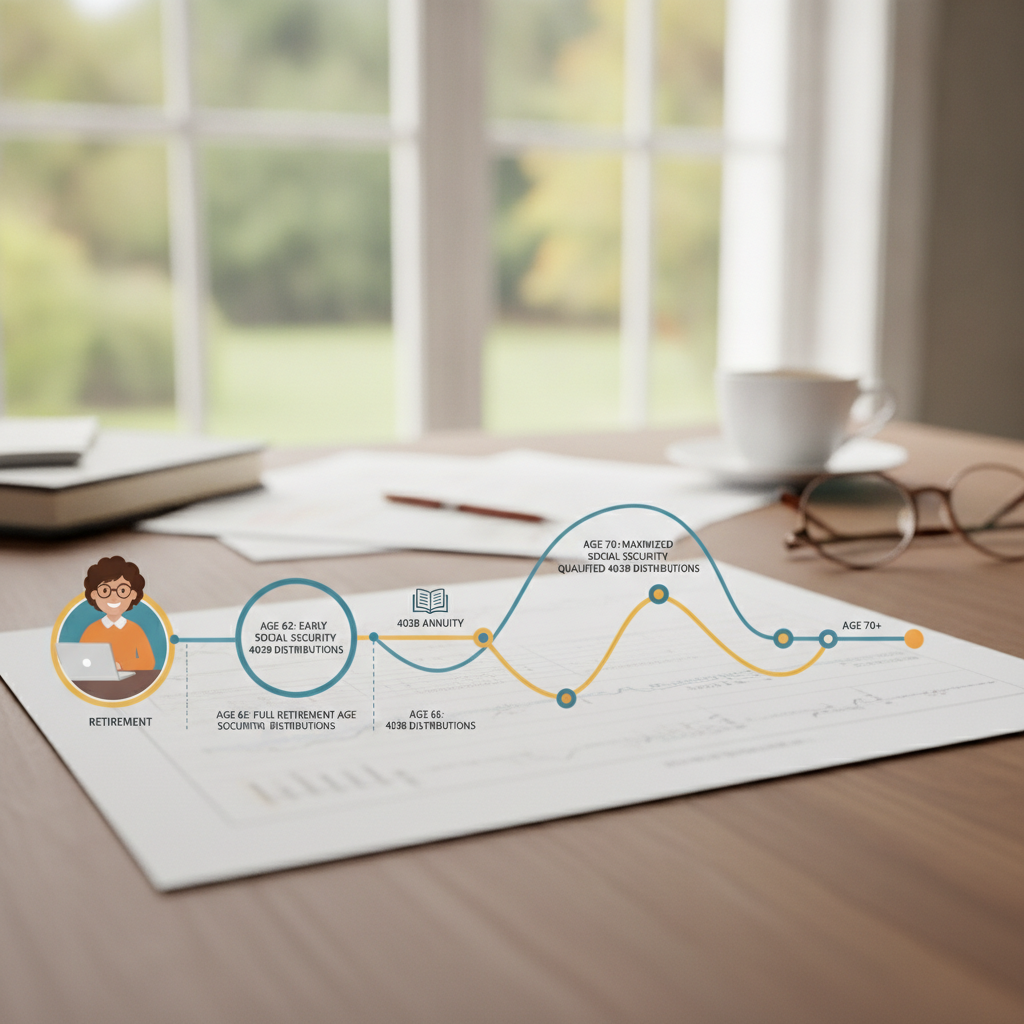
The decision of when to claim Social Security is closely linked to your 403(b) annuity distribution strategy. If you begin drawing from the 403(b) early in retirement to bridge to age 70, you may be able to delay Social Security — capturing a meaningfully higher guaranteed benefit for the rest of your life and for a surviving spouse.
Conversely, if your 403(b) annuity already provides a robust income floor, taking Social Security at 62 or full retirement age may make sense for liquidity reasons or health considerations. These decisions interact with one another in ways that generic calculators cannot fully capture, particularly when significant account balances are involved.
Strategy 5: Plan for IRMAA Thresholds With Precision
IRMAA — the Income-Related Monthly Adjustment Amount — is an often-overlooked cost for high-income retirees. Medicare premiums are not flat; they surcharge upward based on your Modified Adjusted Gross Income from two years prior. A large 403(b) annuity distribution in a single year can trigger elevated Medicare premiums for the following two years.
For 2026, IRMAA surcharges begin at specified income thresholds for individuals and married couples filing jointly. The difference between landing just above versus just below a threshold can represent meaningful premium increases per person per year. Staying aware of these thresholds — and managing distributions, Roth conversions, and other income sources with that awareness — is a discipline that mass-market retirement planning rarely addresses. For current thresholds, reference the Medicare.gov cost overview.
Strategy 6: Evaluate a 1035 Exchange If Your Contract Carries Excessive Fees
Not all 403(b) annuity contracts are created equal. Some legacy contracts — particularly variable annuity products sold in school districts throughout the 1990s and 2000s — carry annual expense ratios that include mortality and expense risk charges, administrative fees, and sub-account expenses that can substantially erode long-term returns.
A Section 1035 exchange allows you to transfer one annuity contract directly to another on a tax-deferred basis, without triggering a taxable event. This can be a meaningful option if your current 403(b) annuity carries high internal fees and you have left your employer (making you eligible for a rollover or exchange). For IRS guidance on 1035 exchanges and tax-free exchanges of annuity contracts, consult IRS Publication 575.
Be cautious about surrender charges — many annuity contracts impose surrender periods of 5–10 years during which early withdrawals or transfers trigger fees. Consult a qualified financial professional to evaluate whether an exchange makes sense given your contract’s specific terms and timeline.
Strategy 7: Use Qualified Charitable Distributions to Reduce Taxable RMDs
If you are age 70½ or older and charitably inclined, a Qualified Charitable Distribution (QCD) allows you to transfer up to a specified annual limit directly from an IRA to a qualified charity. The distribution counts toward your RMD but is excluded from taxable income — a significant advantage for high-balance retirees who do not need RMD income and would otherwise itemize charitable deductions.
Note that QCDs apply to IRAs, not directly to 403(b) accounts. However, if you roll a 403(b) annuity into a traditional IRA upon retirement — a common and generally straightforward move — you gain access to the QCD strategy. For current QCD limits and qualifying organization rules, see IRS guidance on Qualified Charitable Distributions. Consult a qualified tax professional before executing a QCD strategy.
Rolling Over a 403(b) Annuity: When It Makes Sense
The Case for Rolling Into an IRA
When you separate from your employer, you generally have the option to leave your 403(b) annuity in place, roll it to a new employer’s plan, or roll it into an IRA. For HNW individuals, the IRA rollover often provides meaningful advantages: broader investment selection, greater control over distribution timing, access to strategies like QCDs, and potentially lower fees.
However, the rollover decision is not automatically favorable. Some 403(b) plans — particularly those with guaranteed fixed interest rates on older contracts, or those tied to a defined benefit-style guaranteed income feature — may offer contractual benefits worth preserving. Walking away from a 4% or 5% guaranteed crediting rate to roll into an IRA in a low-rate environment, for example, may not serve your interests.
Special Considerations for Educators With a Pension Plus 403(b)
Many public school teachers and state university employees carry both a defined benefit pension and a supplemental 403(b) annuity. This combination is actually a favorable position: the pension provides a baseline guaranteed income floor, which may reduce the urgency of annuitizing the 403(b) balance as well.
When a guaranteed income floor already exists from a pension, the 403(b) annuity balance may be better deployed as a growth and flexibility reserve — available for large expenses, Roth conversion funding, or eventual legacy transfer — rather than converted into another layer of guaranteed income. This is a nuanced analysis that benefits from comprehensive wealth management services tailored to your complete financial picture.
Inherited 403(b) Annuity Rules for Non-Spouse Beneficiaries
Under current law, non-spouse beneficiaries who inherit a 403(b) — including children and other heirs — are generally subject to the 10-year rule for distribution. This means the entire inherited account balance must be distributed within 10 years of the original account holder’s death.
For a high-balance 403(b) annuity, a forced 10-year distribution window can generate significant taxable income for beneficiaries, potentially pushing them into higher tax brackets for a decade. This underscores the importance of proactive planning during the account holder’s lifetime — including Roth conversions, partial annuitization, and beneficiary designation coordination with an estate attorney. For authoritative guidance on inherited retirement accounts, review IRS guidance on retirement plan beneficiaries.
Estate Planning Considerations for 403(b) Annuity Holders
Coordinating Your 403(b) With Your Broader Estate Plan
The federal estate and gift tax exemption is now permanent at $15,000,000 per individual — $30,000,000 per married couple — following the One Big Beautiful Bill Act signed in 2025. This removes much of the artificial urgency that previously drove some gifting decisions, and allows HNW families to plan with greater clarity and without manufactured deadlines.
That said, a large 403(b) annuity balance presents distinct estate planning considerations. Retirement accounts pass outside the probate estate through beneficiary designations — meaning they are not controlled by your will. Keeping beneficiary designations current, properly coordinated with any trust structures, and reviewed after major life events is essential.
State-Level Tax Planning for Florida-Based Educators
Florida imposes no state income tax and no state estate tax, which provides a meaningful structural advantage for retired educators and nonprofit professionals who have established Florida as their domicile. Income drawn from a 403(b) annuity in retirement is subject only to federal taxation — a benefit that compound significantly over a multi-decade retirement for high-balance account holders.
For educators who relocate to Florida from states with income or estate taxes, documenting domicile properly — including voter registration, driver’s license, property records, and time spent in state — is an important step. A qualified estate planning attorney can help ensure your domicile change is properly established.
How to Evaluate the Annuity Contracts Inside Your 403(b)
Key Questions to Ask About Your Current Contract
Before making any distribution, rollover, or annuitization decision, review your existing 403(b) annuity contract with these questions in mind:
- What are the total annual fees, including mortality and expense charges, administrative fees, and sub-account expenses?
- Is there a surrender charge schedule still in effect, and when does it expire?
- What guaranteed interest rates or income benefits are embedded in the contract?
- What payout options are available at annuitization?
- Are there optional riders (income riders, long-term care riders) attached to the contract, and what do they cost?
- What happens to the remaining account value upon death — is there a death benefit, or does it revert to the insurer?
The Role of a Fee-Based Fiduciary in Evaluating 403(b) Annuities
Many 403(b) annuity products are sold by representatives who earn commissions from the insurer. This is a legal and common compensation structure — but it means the incentives of the seller and the interests of the participant may not always align perfectly. When evaluating whether to annuitize, exchange, or roll over a 403(b) balance, working with a fee-based fiduciary adviser — one who acts as a fiduciary in the investment advisory context and discloses compensation arrangements clearly — can provide a more objective framework for the analysis.
At Davies Wealth Management, Thomas Davies brings 30 years of financial services experience, beginning in 1996, to bear on exactly these kinds of complex, high-stakes decisions. If you are ready to explore your options with a knowledgeable partner, we invite you to schedule a discovery conversation with our team.
Free Download
The Complete Florida Retirement Guide
A comprehensive, plain-English guide to retirement planning in Florida — income strategies, tax considerations, Social Security timing, and healthcare planning for Treasure Coast retirees.
Frequently Asked Questions About the 403(b) Annuity
What is the difference between a 403(b) annuity and a regular 403(b) plan?
A 403(b) annuity specifically uses an annuity contract issued by an insurance company as the investment vehicle, while a standard 403(b) custodial account holds mutual funds in a brokerage-style account. Both provide tax-deferred growth and the same contribution limits. The annuity structure introduces features like guaranteed income options, death benefits, and sometimes higher internal expenses that a custodial account does not carry.
Can I roll over a 403(b) annuity to an IRA without paying taxes?
Yes — a direct rollover from a 403(b) annuity to a traditional IRA is a tax-free transaction when executed correctly. The key is ensuring the funds move directly from the 403(b) plan to the IRA custodian without passing through your hands. If you receive a check personally, 20% mandatory withholding applies and you must replace those funds within 60 days to avoid a taxable distribution.
What are Required Minimum Distributions for a 403(b) annuity?
Under current law, RMDs from a 403(b) annuity must begin by April 1 of the year following the year you turn 73. The amount is calculated based on your account balance at the end of the prior year divided by an IRS life expectancy factor. If you have annuitized the contract, the scheduled payments may satisfy the RMD requirement, but this depends on whether the payment schedule complies with IRS regulations. Consult a qualified tax professional to confirm compliance.
Is a 403(b) annuity a good choice for a high-net-worth educator?
A 403(b) annuity can be a valuable component of a high-net-worth educator’s retirement strategy — particularly when the employer matches contributions or when the plan provides access to competitive investment options at low cost. However, for educators who have accumulated large balances, the plan’s investment menu, fee structure, and distribution options should be reviewed carefully. High-balance participants often benefit from a broader set of planning tools beyond what the plan itself provides.
What happens to my 403(b) annuity if I die before annuitizing?
If you die before annuitizing your 403(b) annuity, the contract’s death benefit provisions govern what your beneficiaries receive. Many contracts guarantee at least the return of the account value or the premiums paid, whichever is greater. Beneficiaries will generally be subject to income tax on distributions, and non-spouse beneficiaries must typically distribute the full account within 10 years under current law. Proper beneficiary planning and coordination with your estate attorney can help minimize the income tax impact on your heirs.
Take the Next Step Toward Guaranteed Retirement Income
A well-structured 403(b) annuity strategy — one that accounts for your total income picture, tax exposure, Medicare costs, and estate goals — can provide the income certainty you have worked decades to achieve. But the decisions involved are consequential and often irreversible. Getting them right is worth the investment of time and professional guidance.
If you are approaching retirement with a substantial 403(b) balance and want to explore how an annuity strategy fits into your broader financial plan, start with our free resource:
➡️ Take Our 60-Second Annuity Quiz — Get a clearer picture of whether an annuity strategy belongs in your retirement income plan.
And when you are ready for a more personalized conversation about your 403(b) annuity options, we would be glad to hear from you.
➡️ Book a complimentary phone call — Ready for personalized guidance from a fee-based fiduciary? Let’s talk.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply