
When people search for cheapest financial advice, they’re usually asking a reasonable question: Am I overpaying for guidance I could get elsewhere? It’s a smart question — but the answer depends heavily on how complex your financial life actually is.
🎧 Prefer to listen to the podcast or watch the video? Jump to listen to the podcast & watch the video.
For a 28-year-old with a 401(k) and a savings account, free tools may be entirely sufficient. For a business owner with $3 million in a concentrated stock position, a pending liquidity event, and an estate plan that hasn’t been updated in a decade, “cheap” can carry a very different price tag than whatever the advisor charges.
What Is the Cheapest Way to Get Financial Advice?
The cheapest financial advice is free — from government resources like Investor.gov, employer-sponsored financial wellness programs, or nonprofit credit counseling services. Robo-advisors are the next tier, typically charging 0.25% of assets annually. Human advisors start at roughly $150–$400 per hour for hourly arrangements, or 0.25%–1.5% annually for ongoing management.
But cost and value aren’t the same thing. The sections below break down every option so you can match the right level of advice to your actual situation.
Why the Cheapest Option Isn’t Always the Right Option for HNW Families
Mass-market financial tools are built for mass-market problems. A robo-advisor optimizing a $75,000 IRA uses the same algorithm it uses for a $75,000 account owned by someone with a $5 million portfolio, an irrevocable trust, and a Roth conversion strategy in progress.
The difference between good and poor advice compounds — not just in portfolio returns, but in taxes avoided, estate plans structured correctly, and insurance gaps closed before a crisis. High-net-worth families face financial decisions that simply don’t appear in standard financial planning software:
- Concentrated stock positions with embedded capital gains
- Roth conversion ladders timed around IRMAA thresholds
- Qualified Opportunity Zone investments
- Charitable Remainder Trusts and Donor-Advised Funds
- Multi-generational dynasty trust structures
- Business succession and exit planning
- Private Placement Life Insurance (PPLI) for tax-advantaged investing
- Executive compensation and deferred compensation planning
None of these appear in a robo-advisor’s decision tree. That’s not a criticism — it’s just an accurate description of what those platforms are designed to do. If your situation has moved beyond what a standard platform handles, you’ve likely outgrown it.
The 7 Main Sources of Financial Advice, Ranked by Cost
1. Free Government and Nonprofit Resources
Cost: $0
The SEC’s Investor.gov and the IRS website offer extensive free educational content on investing basics, tax rules, and retirement accounts. The IRS Free File program and VITA (Volunteer Income Tax Assistance) provide free tax preparation for qualifying individuals.
Nonprofit credit counseling agencies (look for NFCC members) offer free or low-cost debt and budget counseling. These are genuinely valuable resources — but they are educational, not advisory. They tell you how the rules work; they don’t tell you what to do given your specific balance sheet, tax situation, and goals.
Best for: Learning fundamentals, understanding tax rules, verifying advisor claims
Not designed for: Personalized strategy, complex tax planning, estate coordination
2. Employer-Sponsored Financial Wellness Programs
Cost: $0 (included in benefits)
Many large employers now offer access to financial counselors, retirement planning tools, and even one-on-one sessions through their benefits packages. These are often underused and genuinely helpful for understanding your 401(k) options or basic benefit elections.
The limitation: these programs are typically provided by the plan administrator and are scoped to plan-level decisions. They’re not comprehensive wealth managers and rarely address the full picture of a senior executive’s or high-income professional’s financial life.
3. Robo-Advisors
Cost: Typically 0.00%–0.35% of assets annually
Robo-advisors like those offered by major custodians use algorithms to build and rebalance portfolios based on your risk tolerance and time horizon. According to NerdWallet’s robo-advisor comparison, fees commonly range from 0.00% to 0.35% annually, with some platforms charging nothing beyond underlying fund expenses.
These platforms work well for straightforward accumulation — a younger investor with a simple portfolio who wants low-cost, hands-off management. They are not designed to handle:
- Tax-loss harvesting at scale across multiple accounts
- Roth conversion analysis tied to IRMAA lookback rules
- Coordination between taxable, tax-deferred, and tax-exempt accounts
- Estate planning or trust account integration
- Concentrated single-stock risk
Consult a qualified financial professional before relying on a robo-advisor for complex multi-account or multi-entity situations.
4. Online Financial Planning Platforms (Advice + Software)
Cost: $30–$500/month, depending on the platform and service level
Several platforms now combine financial planning software with access to human planners via video or messaging. Fees vary widely. Some offer subscription access to certified planners for specific questions; others provide ongoing planning relationships at flat monthly rates.
This tier bridges the gap between fully automated and fully personalized. It can be a reasonable fit for someone with a solid financial foundation who needs occasional expert input — but most of these platforms still have limitations when planning complexity rises significantly.
5. Hourly or Project-Based Financial Planners
Cost: Approximately $150–$400 per hour; flat project fees of $1,500–$7,500 for a comprehensive plan
Hourly planners — often found through the Garrett Planning Network or NAPFA — charge by the hour with no asset-based fee. This is the cheapest financial advice you can get from an actual human professional with fiduciary responsibility. For someone who needs a one-time retirement income analysis or a second opinion on a specific decision, this can be excellent value.
The challenge at higher wealth levels: complex financial situations often require ongoing monitoring and coordination, not a one-time plan. A snapshot from a one-time engagement doesn’t update when tax laws change, your business valuation shifts, or a new Roth conversion opportunity opens up. Complexity tends to favor ongoing relationships over project-based advice.
6. AUM-Based Financial Advisors
Cost: Typically 0.25%–1.5% of assets under management annually
The most common structure for ongoing wealth management is an assets-under-management (AUM) fee — a percentage of the assets the advisor manages on your behalf. According to Kiplinger’s research on advisor fees, average AUM fees for accounts above $1 million have trended lower over the past decade, often falling in the 0.75%–1.0% range, though this varies considerably by firm, service scope, and account size.
At this level, you typically receive:
- Ongoing portfolio management and rebalancing
- Financial planning (retirement, tax, estate)
- Coordination with your CPA and estate attorney
- Proactive strategy adjustments as laws change
- Access to the advisor directly for significant decisions
The key question is whether the advisor is a fiduciary when providing investment-advisory services — meaning they are legally obligated to act in your interest in that capacity — and how they are compensated, including whether they receive commissions on any insurance or annuity products that are separately disclosed.
7. Flat-Fee or Retainer-Based Advisors
Cost: $5,000–$30,000+ annually, depending on complexity
Some advisors — particularly those serving high-net-worth clients — charge a flat annual retainer rather than a percentage of assets. This structure can be cost-effective for large portfolios, since the fee doesn’t automatically scale with account growth.
Flat-fee arrangements often appeal to clients who want comprehensive planning and coordination without feeling that every dollar added to the account increases the advisor’s income. As with AUM-based advisors, ask about the full compensation structure, including any additional product-related compensation that is disclosed separately.
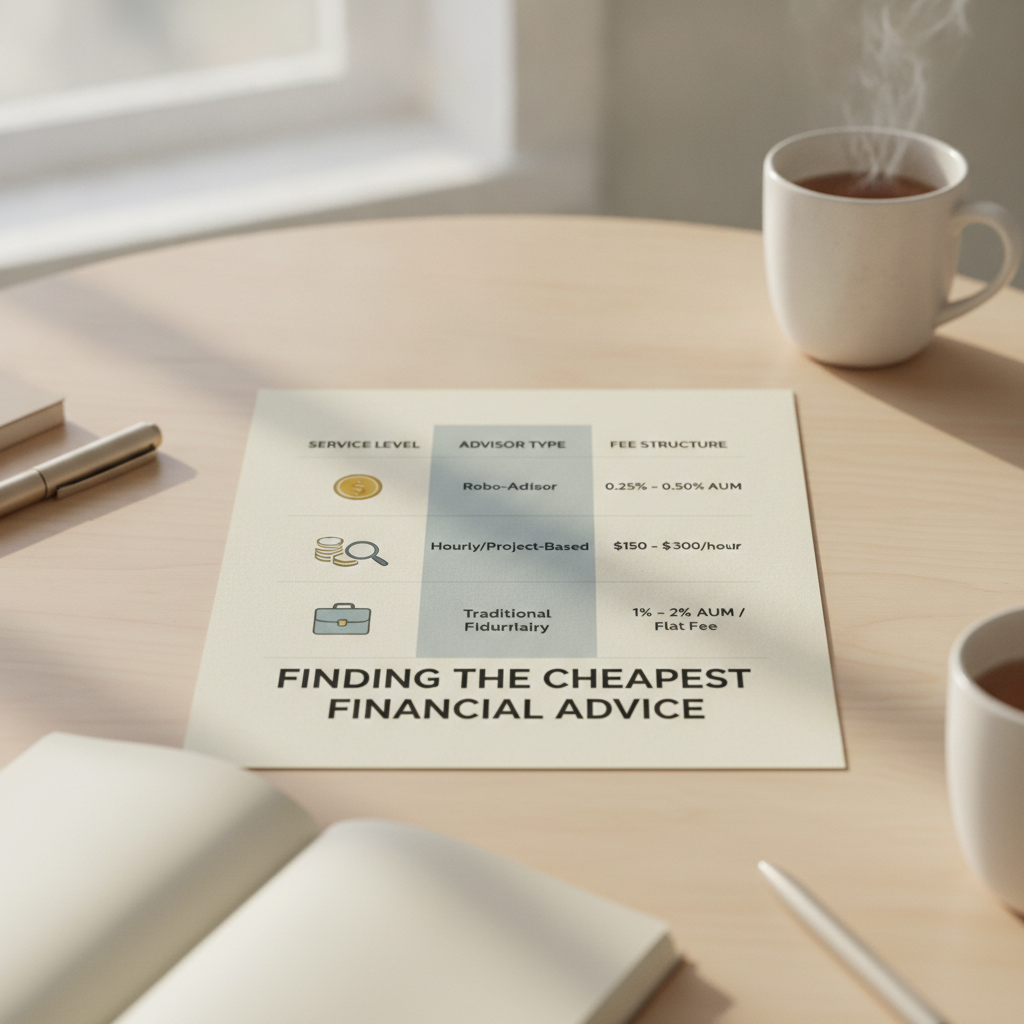
How to Compare the Real Cost of Financial Advice
The Dollar Impact of AUM Fees at HNW Levels
An AUM fee that sounds small in percentage terms represents real dollars at high asset levels. A 1.0% fee on a $2 million portfolio is $20,000 per year. At $5 million, it’s $50,000 annually. These are real numbers worth understanding — not to avoid working with advisors, but to understand what you’re paying and what you should be receiving in return.
The more relevant question: what is the value of what you receive? Strategic tax planning, Roth conversion optimization, estate coordination, and behavioral coaching during volatile markets are difficult to quantify but meaningfully affect long-term outcomes. Consult a qualified financial professional to assess whether the services you’re receiving match the fees you’re paying.
Hidden Costs in “Cheap” Advice
The cheapest financial advice can carry costs that never appear on a fee schedule:
- Investment product costs: Some commission-based advisors earn compensation from the products they recommend. Those costs are embedded in the product, not billed separately. Ask for a full disclosure of all compensation sources.
- Opportunity costs: An advisor who doesn’t know to recommend a Roth conversion in a low-income year, or who doesn’t flag a tax-loss harvesting opportunity before year-end, isn’t costing you a fee — but the missed opportunity has real value.
- Coordination gaps: A financial advisor who doesn’t communicate with your CPA may execute a strategy that creates an unexpected tax bill. The “savings” from using separate, lower-cost providers can evaporate when they don’t coordinate.
What HNW Investors Should Ask Any Advisor
- Are you a fiduciary when providing investment-advisory services?
- How are you compensated — fees, commissions, or both?
- What are all the costs I’ll pay, including fund expenses?
- What is included in your planning services beyond portfolio management?
- Do you coordinate with my CPA and estate attorney?
- How often will we review my full financial picture?
Comparing Financial Advice Options: A Summary Table
| Advice Source | Typical Cost | Personalization | Best Fit |
|---|---|---|---|
| Free gov/nonprofit resources | $0 | None | Education, research |
| Employer financial wellness | $0 (included in benefits) | Low | Plan-level decisions |
| Robo-advisors | 0.00%–0.35% AUM | Low (algorithmic) | Simple accumulation |
| Online advice platforms | $30–$500/month | Moderate | Moderate complexity |
| Hourly/project planners | $150–$400/hr; $1,500–$7,500 flat | Moderate–High | One-time decisions |
| AUM-based advisors | 0.25%–1.5% AUM annually | High | Ongoing HNW management |
| Flat-fee/retainer advisors | $5,000–$30,000+/year | High | Large portfolios, complex planning |
When Is “Cheap” Actually Enough?
Situations Where Low-Cost Options Work Well
Lower-cost advice channels are genuinely appropriate in certain situations:
- You are early in your career with straightforward savings goals
- You have a simple portfolio — primarily index funds in a 401(k) and IRA
- Your tax situation involves standard W-2 income and standard deductions
- You need education, not execution
- You want a second opinion on a specific, narrow question
Situations That Likely Require a Comprehensive Advisor
The calculus shifts meaningfully when any of the following apply:
- Investable assets of $500,000 or more
- A pending business sale, liquidity event, or inheritance
- A concentrated stock position representing a large share of net worth
- Multi-state income or significant real estate holdings
- An estate that warrants trust structures or multi-generational planning
- Executive compensation including deferred comp, equity, or non-qualified plans
- A professional athlete or high-income earner with a compressed earning window
- Medicare and IRMAA exposure from high modified adjusted gross income
If multiple items on that list describe your situation, the cheapest financial advice you can find is probably not the right financial advice for you. The gap between adequate and excellent planning tends to widen as complexity increases.
The Specific Strategies HNW Families Miss Without Qualified Advice
Tax-Loss Harvesting at Scale
Systematic tax-loss harvesting — selling positions at a loss to offset gains — requires active portfolio management and tax awareness. Robo-advisors automate a basic version of this, but sophisticated implementation across a multi-account, multi-entity portfolio requires a human advisor coordinating with your CPA.
Roth Conversion Ladders and IRMAA Planning
Converting traditional IRA assets to Roth in a tax-efficient sequence requires modeling your projected income, current and future tax brackets, and Medicare IRMAA lookback windows (which apply a two-year lag). An incorrectly sized conversion can push you into a higher IRMAA tier, triggering significantly higher Medicare Part B and D premiums. This is precisely the kind of multi-variable optimization that generic tools don’t perform.
Qualified Charitable Distributions (QCDs)
Taxpayers aged 70½ or older can make Qualified Charitable Distributions directly from an IRA to a qualified charity — satisfying Required Minimum Distribution obligations without the amount appearing as taxable income. For philanthropically inclined HNW clients, stacking QCDs strategically can reduce adjusted gross income, potentially avoiding IRMAA surcharges and keeping more income below other threshold-dependent deductions. This is not a strategy that standard planning software typically highlights proactively.
Estate Planning Under the Current Law
The One Big Beautiful Bill Act, signed into law in 2025, permanently set the federal estate and gift tax exemption at $15 million per individual and $30 million per married couple, indexed for inflation going forward. This permanence removes the urgency manufactured by previous sunset deadlines — but it doesn’t eliminate the value of thoughtful estate planning.
State-level estate taxes, portability elections, basis step-up planning, dynasty trusts, and generation-skipping transfer strategies all remain relevant and require coordination between your financial advisor, CPA, and estate attorney. For comprehensive wealth management services that include estate coordination, working with an advisor who actively communicates with your legal team matters.
How to Evaluate Whether You’re Getting What You’re Paying For
Questions to Audit Your Current Relationship
- Has your advisor proactively discussed your tax situation this year — not just your portfolio?
- Do you know what your all-in annual cost is, including fund expenses?
- Has your estate plan been reviewed since major life or law changes?
- Does your advisor coordinate with your CPA and estate attorney?
- Do you have a written financial plan, and is it updated at least annually?
If the answers reveal gaps, the solution may not be finding cheaper advice — it may be finding better advice. If you’d like to explore your options, consider taking the time to schedule a discovery conversation with an advisor who works specifically with high-net-worth families.
Frequently Asked Questions About the Cheapest Financial Advice
What is the cheapest financial advice available to everyone?
The cheapest financial advice is free, available through government sources like Investor.gov and IRS.gov, nonprofit credit counseling services, and many public libraries’ financial literacy programs. These resources provide education and general guidance but do not offer personalized advice for your specific financial situation.
Is cheap financial advice ever good enough for high-net-worth families?
For genuinely simple decisions — understanding how a 401(k) works or reviewing basic investment concepts — free resources are entirely useful. But high-net-worth families with complex tax situations, estate planning needs, or concentrated positions typically require personalized, coordinated advice that free or low-cost tools are not designed to provide.
How much does a financial advisor typically charge per hour?
Hourly financial planning fees generally range from approximately $150 to $400 per hour, depending on the advisor’s credentials, experience, and geographic market. Project-based comprehensive financial plans commonly range from $1,500 to $7,500. Consult a qualified financial professional to understand the full scope of what a given engagement includes before committing.
What is the difference between a cheapest financial advice option and a fiduciary advisor?
Fiduciary status relates to legal obligation, not cost. A fiduciary advisor is legally required to act in your interest when providing investment-advisory services — a standard that not all financial salespeople meet. Some hourly advisors are fiduciaries; some commission-based product salespeople are not. Always ask explicitly about fiduciary scope and how the advisor is compensated.
Are robo-advisors the cheapest financial advice for investing?
Robo-advisors are among the cheapest options for automated portfolio management, with many charging 0.00%–0.35% annually. However, they do not provide personalized tax planning, estate coordination, or the ability to address complex financial situations — which means they may not be the most cost-effective option for high-net-worth families whose planning needs exceed what an algorithm can address.
The Bottom Line on Cheapest Financial Advice
The cheapest financial advice isn’t always bad — but it is always limited. Free resources, robo-advisors, and hourly planners each serve a real purpose for the right situation. The question is whether your financial situation matches the tool.
For individuals and families with significant assets, complex tax exposure, or multi-generational wealth goals, the real cost of cheap advice often emerges not on a fee schedule but in missed opportunities, uncoordinated strategies, and planning gaps. The most cost-effective financial advice is the advice that serves your actual complexity — whatever that costs.
At Davies Wealth Management, Thomas Davies brings 30 years of experience in financial services to working with high-net-worth individuals, executives, professional athletes, and business owners. The firm’s minimum is $500,000 in investable assets. Consult a qualified financial professional for guidance specific to your situation.
Not sure if your current financial plan is working as hard as it should? Take our Financial Wellness Quiz to get a quick read on where you stand — and where there may be room to do better.
Ready for a personalized conversation? Book a complimentary phone call with Davies Wealth Management — no obligation, no sales pressure, just a straight conversation about your situation.
This content is for general educational purposes only and does not constitute individualized investment advice. Past performance does not guarantee future results. Investment-advisory services are offered by Davies Wealth Management, LLC, an investment adviser registered with the State of Florida. Registration does not imply a certain level of skill or training. Please consult appropriately qualified financial, tax, or legal professionals regarding your specific circumstances. This content was produced with AI assistance and may contain errors. Please verify any figures or claims before relying on them.
Listen & Watch
Prefer audio or video? We’ve got you covered.
Leave a Reply